Japan Bond Yields Surge: Could Japanese Money Leave Global Markets?
Japan’s Bond Yields Are Surging: Could Trillions in Japanese Money Start Coming Home?
For decades, Japan played an unusual but enormously important role in global financial markets.
Interest rates at home were exceptionally low.
Japanese banks, insurers, pension funds and other institutional investors therefore searched overseas for better returns.
That helped direct enormous amounts of Japanese capital into U.S. Treasuries and other international bond markets.
Now that relationship is beginning to change.
Japan's 10-year government-bond yield has climbed above 3%, reaching levels not seen in roughly three decades, while the Bank of Japan has raised its policy rate to 1.25%, its highest in 31 years.
The immediate story is about Japanese bonds.
But the bigger question is global:
What happens if Japanese investors no longer need to send as much money overseas to earn attractive returns?
The answer could matter for U.S. Treasury yields, global borrowing costs, the yen and ultimately stock-market valuations around the world.
Why Are Japanese Bond Yields Rising?
Japan spent decades fighting weak inflation and sluggish economic growth.
That produced extraordinarily loose monetary policy.
For years, the Bank of Japan kept interest rates around or below zero and purchased huge quantities of government bonds.
That environment is disappearing.
Inflation has become more persistent, energy prices remain elevated and the BOJ has shifted toward preventing inflation from overshooting its target.
In September, the Bank of Japan raised its policy rate by 25 basis points to 1.25%.
Governor Kazuo Ueda has also signalled that further increases remain possible if inflation pressures continue.
Japan's bond market is adjusting to this new reality.
The benchmark 10-year Japanese government bond yield climbed to approximately 3.075% on September 24, its highest level since 1996.
That is a major change for a country where investors became accustomed to almost no return from government bonds.
Why Should a U.S. or Indian Investor Care About Japanese Bonds?
Because Japan is one of the world's largest sources of capital.
Japanese investors accumulated enormous overseas portfolios during the country's ultra-low-rate era.
They became important buyers of:
- U.S. Treasuries
- European government bonds
- Australian bonds
- foreign corporate debt
- international equities
The logic was relatively straightforward.
If Japanese bonds yielded almost nothing, investors had a strong incentive to look overseas.
But that calculation changes when Japanese bonds begin offering significantly higher returns.
The global question becomes:
Why take foreign-exchange and overseas-market risk if attractive yields are increasingly available at home?
The Potential Capital-Flow Chain
The mechanism can be simplified:
Higher Japanese interest rates
↓
Higher Japanese government-bond yields
↓
Domestic bonds become more attractive
↓
Japanese institutions need less foreign exposure
↓
Demand for overseas bonds potentially weakens
↓
Global bond yields face additional upward pressure
↓
Financing costs remain elevated
↓
High-valuation stocks face a tougher environment
This does not require Japanese investors to suddenly dump trillions of dollars of overseas assets.
Even a reduction in new buying can matter.
Japan has historically been such an important marginal source of demand that a gradual change in allocation could influence global markets.
Is Japanese Money Already Starting to Come Home?
There are early signs that behaviour is changing.
Japanese investors sold a net 3 trillion yen, or roughly $19 billion, of overseas debt through August 22, according to official data reported by Reuters.
That represented the largest year-to-date reduction since the global bond selloff of 2022.
Japanese corporate pension funds are also showing greater interest in domestic bonds.
A J.P. Morgan Asset Management survey of 82 Japanese corporate pension funds found the net proportion planning to increase domestic bond holdings was the highest since the survey began in 2008.
Japanese megabanks have also begun cautiously rebuilding government-bond portfolios, while life insurers have been repositioning toward newer, higher-coupon domestic bonds.
This is not yet a mass repatriation.
But it suggests that the incentives are changing.
Japan Does Not Need to Sell U.S. Treasuries for This to Matter
This distinction is critical.
The dramatic scenario would be:
Japan aggressively sells its overseas assets.
There is little evidence of such a wholesale move.
The subtler scenario may matter more:
Japan simply buys fewer overseas bonds in the future.
Imagine that a major buyer historically purchases $100 billion of overseas debt each year.
If that buyer reduces future purchases to $60 billion because domestic bonds have become more attractive, nothing has technically been “dumped.”
But global bond markets have still lost $40 billion of incremental demand.
That can influence prices.
And because bond prices and yields move in opposite directions, weaker demand can contribute to higher yields.
The End of Japan as the World's Cheap-Money Machine?
Japan's importance goes beyond bond ownership.
For decades, the yen also served as one of the world's major funding currencies.
Investors could borrow cheaply in yen and invest the proceeds in higher-yielding assets elsewhere.
This is commonly called the yen carry trade.
The simplified trade looked like:
Borrow yen cheaply → convert to another currency → buy higher-yielding assets → earn the yield difference.
The strategy became particularly attractive when U.S. rates rose sharply while Japanese rates remained near zero.
But the economics become less compelling when Japanese rates rise.
That creates another potential transmission channel:
BOJ tightening → more expensive yen funding → less attractive carry trades → potential reduction in global leverage.
This is one reason changes in Japanese monetary policy can affect markets far beyond Tokyo.
The “Reverse Carry Trade” Is Emerging
The changing yield environment has even created discussion of a potential reverse carry trade.
Instead of borrowing cheaply in Japan to invest elsewhere, some international investors may increasingly find Japanese fixed income attractive itself.
Japan's yield curve has become unusually steep.
That means investors can potentially earn more attractive returns in longer-dated Japanese bonds than they could during the ultra-low-rate era.
This represents a remarkable reversal.
Japan is gradually changing from:
a source of cheap global funding
toward
a market capable of attracting fixed-income capital.
Why This Could Matter for U.S. Treasury Yields
The timing is especially important because U.S. yields are already elevated.
The U.S. 10-year Treasury yield recently moved above 5%, driven by strong economic growth, inflation concerns and expectations that monetary policy could remain restrictive.
Read U.S. 10-Year Yield Back Above 5%: Why Strong Growth Is Now a Risk for Stocks for our analysis of why strong U.S. economic data is pushing yields higher.
Now add another potential factor:
less incremental Japanese demand for Treasuries.
The U.S. Treasury market is already absorbing enormous government borrowing.
If one of its historically important foreign investor bases becomes less aggressive, investors may demand somewhat higher yields to absorb that supply.
That does not mean Japan alone determines U.S. Treasury yields.
It does mean Japan could become another piece of an already complicated global bond-market puzzle.
5% May Not Be the Only Level Investors Need to Watch
Markets spent much of September focused on whether the U.S. 10-year Treasury yield could remain above 5%.
But the more important issue may be whether global bond yields are undergoing a broader structural repricing.
Several forces are pushing in the same direction:
- persistent inflation
- high energy prices
- large government borrowing
- stronger-than-expected economic growth
- renewed central-bank tightening
- reduced Japanese demand for foreign bonds
If those forces persist, the debate could eventually move beyond whether 5% is the ceiling.
The more important question would become:
What level of bond yields begins seriously competing with equities for global capital?
Why Rising Global Yields Matter for AI and Technology Stocks
Technology companies are particularly important in this discussion.
Many high-growth companies are valued based partly on profits expected many years into the future.
Higher bond yields increase the discount rate investors use to value those future earnings.
In simplified terms:
Higher global yields → higher discount rates → lower present value of future earnings.
Artificial intelligence provides a powerful counterforce because AI-related companies are generating unusually strong growth expectations.
That creates a continuing battle between:
AI earnings growth
and
the rising global cost of capital.
Read AI Stocks vs 5.2% Treasury Yields: Is the S&P 500 Too Dependent on AI? for the broader valuation debate.
AI Investment Could Also Keep Global Rates Higher
There is another connection.
Technology companies are spending enormous amounts on:
- data centres
- AI chips
- high-bandwidth memory
- electricity infrastructure
- networking
- construction
- cloud capacity
That investment supports economic growth.
If AI capital expenditure keeps economies stronger than expected, central banks may have less room to cut rates.
This creates an unusual feedback loop:
AI investment → stronger demand → resilient growth → persistent inflation → higher interest rates → pressure on AI valuations.
So the AI boom may simultaneously support technology earnings and contribute to the macroeconomic environment challenging their valuations.
Japan Is Joining a Global Tightening Cycle
The BOJ is not acting in isolation.
Major central banks have again become more focused on inflation risks.
The Federal Reserve has tightened.
The European Central Bank has also responded to persistent price pressures.
The Bank of Japan is moving away from decades of exceptionally easy policy.
That creates a much different environment from the years when global markets could rely on abundant cheap money.
The global monetary backdrop is increasingly becoming:
Higher rates in the U.S.
Higher rates in Europe
Higher rates in Japan
That combination could have broader consequences than any one central bank acting alone.
Oil Makes Japan's Problem More Complicated
Japan is heavily dependent on imported energy.
High oil prices therefore matter directly to Japanese inflation.
When energy prices rise, Japan's import costs increase.
A weaker yen can amplify that pressure because commodities are largely priced in dollars.
This creates a difficult cycle:
High oil + weak yen → higher import costs → inflation pressure → BOJ tightening → higher Japanese yields.
That is another reason the Bank of Japan may remain focused on inflation even after raising rates to a three-decade high.
What Happens to the Yen?
Normally, higher domestic interest rates should support a currency.
The logic is simple:
Higher Japanese yields make yen-denominated assets more attractive.
But currencies are influenced by relative rates, not simply domestic rates.
If the Federal Reserve is also raising rates aggressively, the yield advantage of U.S. assets may remain substantial.
That helps explain why the yen did not strengthen dramatically following the latest BOJ increase.
Investors therefore need to watch both sides:
How quickly does the BOJ tighten?
and
How quickly do the Fed and other central banks tighten?
The relative answer could determine the yen's next major move.
Why This Matters for India
The Japanese bond story may appear distant from Indian equities.
It is not.
If Japanese investors allocate more money domestically and global bond yields remain elevated, international capital becomes more expensive.
India then competes against increasingly attractive fixed-income opportunities in developed markets.
For example:
Japanese bonds offer improving domestic returns.
U.S. Treasuries offer yields around 5%.
Indian equities offer potentially higher long-term growth but also greater volatility.
Global investors must compare these opportunities.
Higher developed-market yields therefore raise the return hurdle for emerging-market assets.
At the same time, high oil prices create another challenge for India because the country imports much of its crude requirements.
That means India could simultaneously face:
higher global yields + expensive oil.
Both can influence foreign institutional flows, inflation and the rupee.
Could Asian Capital Flows Become More Regional?
There is another possibility.
As Japanese yields rise, more Asian capital could remain within the region.
Japan becomes more attractive for fixed-income investors.
Vietnam has recently entered FTSE's emerging-market universe.
India continues attracting long-term institutional interest.
South Korea and Taiwan remain central to the AI semiconductor cycle.
This could gradually make Asian capital allocation more diversified.
Read Vietnam Joins Emerging Markets: Could a $6 Billion FTSE Upgrade Trigger the Next Big Asian Stock-Market Re-Rating? for another example of how the Asian investment landscape is changing.
Three Scenarios for Global Markets
Scenario 1: Japanese Yields Stabilize
The BOJ raises rates gradually.
Inflation begins stabilizing.
Japanese bond yields find an equilibrium.
Japanese institutions increase domestic allocations slowly rather than aggressively.
Potential implication: global markets absorb the change without major disruption.
Scenario 2: Japanese Yields Continue Rising
Inflation remains persistent.
The BOJ continues tightening.
Domestic bonds become increasingly attractive.
Japanese institutions reduce foreign bond purchases.
Potential implication: upward pressure on global term premiums and borrowing costs could persist.
Scenario 3: Rapid Repatriation
A sharp yen move or major policy shift encourages Japanese investors to bring capital home quickly.
Carry trades unwind.
Foreign bonds and risk assets experience simultaneous selling.
Potential implication: global financial-market volatility could rise sharply.
This is the more extreme scenario and should not be treated as the base case, but it explains why global investors closely monitor Japan.
What Investors Should Watch Next
The most useful indicators are:
- Japan 10-year government-bond yield
- Japan 30-year government-bond yield
- BOJ policy rate
- Japanese inflation
- USD/JPY
- Japanese overseas bond purchases
- Japanese pension-fund allocations
- U.S. 10-year Treasury yield
- global term premiums
- oil prices
- central-bank guidance
Readers can monitor major Japanese, U.S., European and Indian equity markets through the LiveWorldMarket Global Indices & Futures Hub.
The Bigger Picture: Japan May No Longer Export Cheap Money Forever
For decades, Japan's ultra-low interest rates were a structural feature of global markets.
Cheap yen funding encouraged global carry trades.
Low domestic yields encouraged Japanese institutions to buy overseas bonds.
That provided additional capital to markets around the world.
Now the underlying economics are changing.
Japanese rates are rising.
Japanese government bonds are offering more meaningful yields.
Domestic fixed income is becoming increasingly competitive with overseas assets.
The transformation does not require trillions of dollars to suddenly return to Japan.
A gradual shift may be enough.
If Japanese institutions simply become less willing to finance the rest of the world's bond markets, one of the global financial system's most reliable sources of incremental demand could become smaller.
And that is why a 3% Japanese government-bond yield can matter to an investor holding the S&P 500, Nasdaq, Nifty 50 or almost any other major risk asset.
The bigger question is no longer simply:
“How high will Japanese bond yields go?”
It is:
“What happens to global asset prices when one of the world's largest pools of savings finally has a reason to stay home?”
That could become one of the most important—and least appreciated—cross-market stories of 2026.
Related LiveWorldMarket Analysis
U.S. 10-Year Yield Back Above 5%: Why Strong Growth Is Now a Risk for Stocks
AI Stocks vs 5.2% Treasury Yields: Is the S&P 500 Too Dependent on AI?
Disclaimer: This article is for informational and educational purposes only. It does not constitute investment advice or a recommendation to buy or sell securities or financial instruments. Bond yields, currencies, monetary policy and financial markets can change rapidly.
Comments (0)
Be the first to comment.
About the author
NISM-Series-X-A Investment Adviser Level 1 examination completed
Amit writes about Indian equity markets, technical analysis, macro themes and the day-to-day mechanics of trading, with a focus on making the flow of global markets legible for retail investors. He has completed the NISM-Series-X-A Investment Adviser Level 1 examination.
You May Also Like
US 10-Year Treasury Yield Below 5%: Growth Shock Warning?
Central Banks & Rates · Oct 23, 2026 · 17 min read
US 10-Year Treasury Yield Falls Below 5% Despite $114 Oil: Is the Bond Market Warning of a Global Growth Shock? Something unusual is happening across global financial markets. The yield on the benchmark U.S. 10-year Treasury has fallen sharply below the psychologically important 5% level, even as Brent crude oil has surged toward $114 per barrel and technology stocks have…
Read more...
Brent Crude Tops $110: Impact on Indian Stocks & Earnings
Global Markets & Economy · Oct 22, 2026 · 14 min read
Brent Crude Tops $110: Why Indian Airlines, Paints and Tyre Stocks Face a Hidden Earnings Risk Brent crude oil has climbed above $110 per barrel, intensifying concerns that rising global energy prices could squeeze corporate profit margins, increase India's import costs and create further volatility in domestic equities. On October 22, Brent futures traded above $111 after…
Read more...
India Optical Fibre Exports Jump 158%: AI's Hidden Winners
Global Markets & Economy · Oct 21, 2026 · 12 min read
India's Optical Fibre Exports Jump 158% as Japan's Chip Shipments Surge 49%: The Hidden Winners of the AI Infrastructure Boom Artificial intelligence may be transforming the technology industry, but some of its most important economic beneficiaries are not necessarily the companies developing AI models. They may be the businesses manufacturing the physical infrastructure that…
Read more...
Nasdaq Rises 1.1%, KOSPI Falls 3.6%: AI Stocks and India Impact
Global Markets & Economy · Oct 20, 2026 · 12 min read
Nasdaq Jumps 1.1% but KOSPI Crashes Over 3%: Why the AI Stock Rebound Is Failing in Asia—and What It Means for India Global technology stocks are sending conflicting signals. On Monday, October 19, the Nasdaq Composite gained 1.11%, recovering part of the losses suffered during the previous week's technology selloff. U.S. semiconductor stocks also rebounded, with the…
Read more...
Jio IPO 2026: $108 Billion Valuation Amid Global AI Selloff
Market Valuation & Behaviour · Oct 19, 2026 · 14 min read
Jio IPO at $108 Billion Amid Global AI Stock Selloff: Can India's Biggest IPO Defy the Tech Market Rout? India is preparing for what could become its largest-ever initial public offering at a time when global investors are reassessing technology valuations, artificial intelligence spending and the financial sustainability of digital infrastructure. Jio Platforms, the digital…
Read more...
China GDP Grows 4.5% as Oil Falls: Can India Stocks Benefit?
Global Markets & Economy · Oct 19, 2026 · 12 min read
China GDP Grows 4.5% as Oil Falls Toward $108: Could India and Asian Stocks Benefit From a Global Market Reset? China's economy expanded faster than expected in the third quarter of 2026, but the latest economic data reveals a growing divide between its powerful export industries and weak domestic demand. At the same time, global crude oil prices declined toward $108 per…
Read more...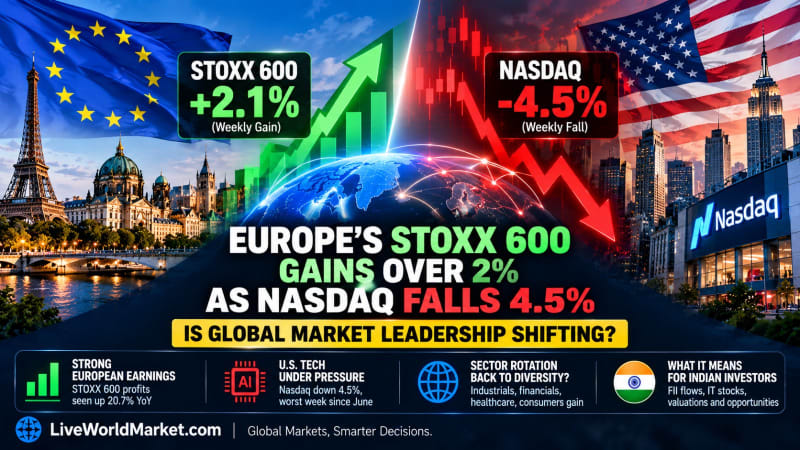
STOXX 600 Rises 2% as Nasdaq Falls 4.5%: Is Europe Taking the Lead?
Global Markets & Economy · Oct 18, 2026 · 13 min read
Europe’s STOXX 600 Gains Over 2% as Nasdaq Falls 4.5%: Is Global Stock Market Leadership Shifting? Europe's stock markets delivered their strongest week since June while U.S. technology shares suffered their worst weekly decline in months. The divergence raises a critical question for global investors: Is the market beginning to reward diversified earnings growth instead of…
Read more...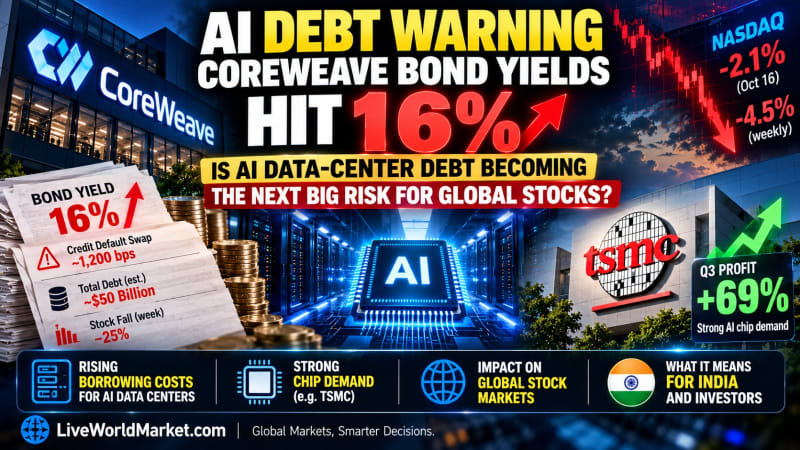
CoreWeave Bond Yields Hit 16%: AI Data Center Debt Risks
Technology & Sectors · Oct 17, 2026 · 13 min read
CoreWeave Bond Yields Hit 16%: Is AI Data-Center Debt Becoming the Next Big Risk for Global Stocks? The artificial intelligence boom has entered a new phase. Investors are no longer asking only how much money AI companies can earn. They are increasingly questioning how much it costs to finance the infrastructure supporting that growth. This week, CoreWeave, a U.S.-based AI…
Read more...
Indonesia Stocks Crash 11.57%: Will MSCI Downgrade Benefit India?
India & Global Connections · Oct 16, 2026 · 12 min read
Indonesia Stocks Plunge 11% as MSCI Proposes Downgrade: Could India and Other Emerging Markets Benefit? Indonesia's stock market has suffered its sharpest one-day decline in nearly three decades, but the bigger story extends far beyond Jakarta. A proposed MSCI downgrade could eventually force global index funds to remove Indonesian equities from their portfolios, potentially…
Read more...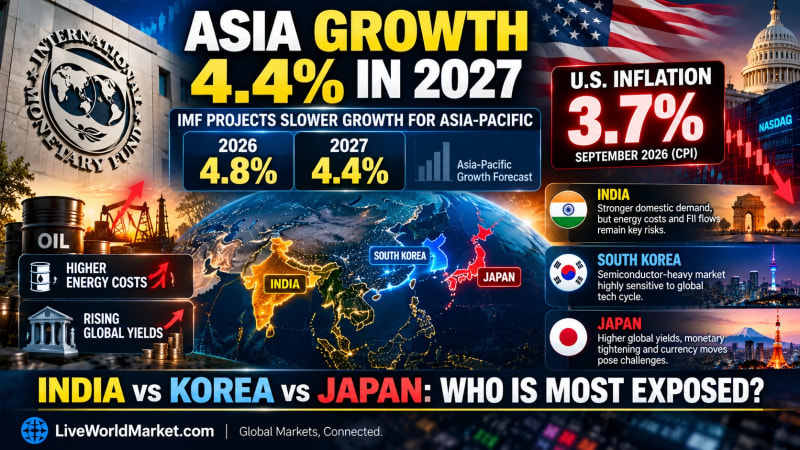
IMF Asia Growth 4.4%, US CPI 3.7%: Which Stocks Are at Risk?
News · Oct 15, 2026 · 12 min read
IMF Sees Asia Growth Slowing to 4.4% as U.S. Inflation Hits 3.7%: Which Stock Markets Are Most Vulnerable? Asia's stock markets are facing a critical test as two major economic developments collide: the International Monetary Fund's warning about slower regional growth and an unexpected rise in U.S. inflation. The IMF's October Asia-Pacific outlook projects regional economic…
Read more...