AI Infrastructure Boom: $126 Billion Flows Into Chips, Data Centres and Power
The AI Boom Is Entering a New Phase: $126 Billion Is Pouring Into Chips, Data Centres and Power
For the past several years, the artificial-intelligence investment story has largely revolved around one question:
Which company will build the most powerful AI chips and models?
That question helped fuel enormous gains across semiconductor and technology stocks.
But the AI investment cycle is beginning to change.
The next phase may be less about individual AI stocks—and much more about the enormous physical infrastructure required to keep artificial intelligence running.
Across Asia-Pacific, companies connected to high technology have raised approximately $125.8 billion through equity and convertible-bond deals in 2026, more than three times the amount raised a year earlier.
The money is increasingly flowing toward three critical areas:
Chips → Data Centres → Power
That raises an important question for global investors:
Is the next major AI investment opportunity shifting from the companies creating AI to the infrastructure required to power it?
Asia's AI Capital-Raising Boom Is Accelerating
The scale of capital flowing through Asian markets is remarkable.
Asia-Pacific companies have raised approximately $327.1 billion through equity deals in 2026, according to LSEG data.
That is around 53% higher than a year earlier.
High-technology companies alone have raised approximately $125.8 billion, accounting for around 38% of the region's total fundraising.
The number is important because it shows that the AI boom is increasingly becoming a capital-investment cycle, not simply a stock-market theme.
Companies are raising enormous amounts of money to build the infrastructure required for the next stage of artificial intelligence.
That includes:
- AI processors
- memory
- semiconductor manufacturing
- data centres
- networking
- optical communications
- electricity generation
- transmission infrastructure
- cooling systems
The AI boom is increasingly becoming physical.
The AI Investment Chain Is Getting Much Bigger
Every AI prompt looks digital.
The infrastructure behind it is anything but.
When someone asks an AI assistant a question, generates an image or asks an AI agent to perform a task, that request eventually reaches physical computing infrastructure.
The chain looks roughly like this:
AI applications
↓
Cloud computing
↓
Data centres
↓
GPUs and AI accelerators
↓
High-bandwidth memory
↓
Networking
↓
Electricity
↓
Power grids
This explains why the AI investment opportunity is broadening beyond traditional technology companies.
The more AI people use, the more infrastructure is required behind it.
Phase One Was Chips
The first phase of the AI boom was dominated by semiconductors.
Training increasingly powerful AI models required enormous computing resources.
That created extraordinary demand for:
- GPUs
- AI accelerators
- high-bandwidth memory
- advanced semiconductor manufacturing
- semiconductor equipment
South Korea provides one of the clearest examples.
SK hynix recently raised $26.5 billion in a Nasdaq share sale, according to Reuters.
The company has become one of the most important suppliers of high-bandwidth memory used in AI computing.
This connects directly with the surge in South Korean semiconductor exports and provides further evidence that AI demand is moving beyond stock prices into the real industrial economy.
The first AI investment equation was therefore relatively straightforward:
More powerful AI → more chips.
But the equation is now becoming much larger.
Phase Two Is Data Centres
AI chips need somewhere to operate.
That means data centres.
And AI data centres are dramatically different from conventional computing facilities.
Large AI clusters can contain enormous numbers of processors operating simultaneously.
That requires:
- huge buildings
- advanced cooling
- fibre-optic networking
- power-management systems
- backup electricity
- specialised servers
As AI models become larger and AI-agent usage expands, data-centre capacity could become one of the biggest constraints on the industry.
This is why capital is increasingly flowing toward data-centre operators.
Australian AI infrastructure company Firmus and Singapore-based data-centre operator DayOne are among companies that could potentially raise billions of dollars.
The AI investment narrative is therefore expanding from:
Who makes the chips?
to:
Where will all those chips actually run?
Phase Three Could Be Power
This may ultimately become the most important part of the story.
Data centres consume enormous amounts of electricity.
The more AI infrastructure companies build, the more power they require.
That creates a simple relationship:
More AI
↓
More computing
↓
More data centres
↓
More electricity
And electricity infrastructure cannot be expanded overnight.
New demand may require:
- power plants
- renewable generation
- nuclear energy
- natural gas
- transmission lines
- transformers
- battery storage
- grid upgrades
This means the AI investment boom is gradually becoming an energy-infrastructure story.
The next major bottleneck for AI may not necessarily be chips.
It could be electricity.
Why Power Could Become AI's Biggest Constraint
Technology companies can order more processors.
Semiconductor manufacturers can gradually expand production.
But adding large amounts of electricity capacity is much more difficult.
Power projects can take years to approve and build.
Transmission infrastructure can take even longer.
That creates an important mismatch.
AI demand can grow exponentially.
Electricity infrastructure generally grows gradually.
If AI data-centre construction continues accelerating, power availability could become increasingly valuable.
That may create opportunities across industries that investors historically would not have considered part of the technology sector.
AI Is Blurring the Line Between Technology and Utilities
Traditionally, investors viewed technology companies and utilities as completely different sectors.
Technology represented growth.
Utilities represented stable, defensive businesses.
AI is beginning to blur that distinction.
Technology companies increasingly need enormous amounts of reliable electricity.
Utilities need enormous amounts of capital to meet that demand.
The result is a new relationship:
Technology growth creates utility investment.
This could make electricity networks, generation capacity and grid infrastructure increasingly important components of the AI investment ecosystem.
The $126 Billion Figure Shows Investors Are Funding the Buildout
The strongest evidence comes from capital markets themselves.
Investors are providing large amounts of money to companies that can demonstrate genuine exposure to AI infrastructure.
But investors are also becoming more selective.
The market is increasingly distinguishing between:
companies that simply tell an AI story
and
companies generating real earnings from the AI buildout.
That distinction may become extremely important.
As the AI cycle matures, simply adding “AI” to a corporate strategy may no longer be enough.
Investors increasingly want evidence of:
- contracts
- revenue
- capacity utilisation
- cash flow
- infrastructure demand
- sustainable earnings
That could mark an important transition in the AI market.
Asia Is Becoming the Physical Backbone of AI
Much of the AI software innovation receives attention in the United States.
But a large part of the physical AI supply chain sits in Asia.
Consider the ecosystem:
United States
AI models, cloud platforms and chip design.
Taiwan
Advanced semiconductor manufacturing.
South Korea
High-bandwidth memory and memory chips.
Japan
Semiconductor equipment and advanced materials.
China
AI infrastructure, manufacturing and domestic semiconductor expansion.
Singapore
Data centres and regional cloud infrastructure.
India
Rapidly expanding data-centre, digital and cloud demand.
The AI boom is therefore not simply a Silicon Valley story.
It is becoming one of the largest infrastructure investment cycles across Asia.
Readers can track the major Asian, U.S., European and Indian equity markets through the LiveWorldMarket Global Indices & Futures Hub.
China Is Becoming an Important Part of the AI Infrastructure Cycle
China's latest economic data reinforce this trend.
The country's official manufacturing PMI returned to expansion in September, rising to 50.1 from 49.8 in August.
Production improved to 51.7, while new orders reached 50.5.
AI-related industrial activity helped support manufacturing even while property and domestic demand remained weak.
This reinforces the idea that China's economy is becoming increasingly divided between its technology-led industries and weaker traditional sectors.
Read China's Economy Is Splitting in Two: AI Profits Are Surging While Traditional Industries Struggle for our detailed analysis of this divergence.
China Is Building Its Own AI Supply Chain
China is also investing heavily in domestic semiconductor capacity.
Yangtze Memory Technologies is among the companies reportedly considering major fundraising.
The broader objective is clear.
China wants greater control over:
- AI chips
- memory
- semiconductor manufacturing
- cloud computing
- networking
- data centres
U.S. technology restrictions have accelerated this push.
Rather than slowing China's AI ambitions entirely, restrictions have also strengthened incentives to develop domestic alternatives.
That creates a global semiconductor race.
Read Trump-Xi Meeting Could Be the Next Big Catalyst for AI and Semiconductor Stocks for more on the geopolitical side of the AI supply chain.
AI Is Moving From Training to Inference
Another reason infrastructure demand could remain strong is the transition from training AI models to using them at scale.
Training requires enormous computing resources.
But inference happens every time somebody actually uses AI.
Every:
- AI search
- chatbot conversation
- generated image
- coding request
- AI-agent task
requires computing capacity.
As AI adoption expands, inference could become an increasingly important source of demand.
AI agents could accelerate this dramatically.
An agent asked to book a trip may need to perform dozens of computing operations behind the scenes.
That means:
More AI users → more inference → more data-centre utilisation → more electricity demand.
Read AI Agents Are Becoming the New Catalyst for Chip Stocks for our analysis of this next phase of consumer AI demand.
AI Infrastructure Could Become a Multi-Trillion-Dollar Cycle
The scale of planned global AI investment is extraordinary.
Major technology companies and AI developers are committing hundreds of billions of dollars to computing infrastructure.
Anthropic, for example, expects to spend at least $518 billion over a decade building AI infrastructure with several partners, according to an IPO prospectus reviewed by Reuters.
OpenAI's Stargate initiative has also outlined a roughly $500 billion AI infrastructure ambition.
This suggests the current $126 billion Asian fundraising wave could represent only one part of a much larger global investment cycle.
But enormous spending also creates enormous expectations.
Eventually, AI needs to generate enough revenue to justify the infrastructure being built.
The Biggest Risk: What If AI Revenue Cannot Justify the Spending?
This is where the investment story becomes more complicated.
AI infrastructure is extremely expensive.
Data centres require enormous upfront capital.
Chips become obsolete quickly.
Electricity contracts can be long-term.
Debt financing can become expensive when interest rates are high.
If AI revenue grows slower than expected, companies could find themselves with:
large infrastructure commitments + high financing costs + insufficient returns.
This is why investors should not assume that every company connected to AI infrastructure will automatically benefit.
The key question is increasingly:
Who earns enough money from AI to justify the capital being invested?
Credit Markets Are Beginning to Ask That Question
Signs of caution are already emerging.
Some debt linked to major AI infrastructure projects has weakened as investors reassess how much borrowing the sector can absorb.
The concern is not necessarily that major technology companies will default.
Many have exceptionally strong balance sheets.
The issue is return on investment.
If trillions of dollars are invested in AI infrastructure, the industry eventually needs enormous recurring revenue to generate acceptable returns.
That could make AI revenue growth versus AI capital expenditure one of the most important financial ratios of the next several years.
High Bond Yields Make the Calculation Harder
The AI infrastructure boom is occurring in a very different interest-rate environment from previous technology investment cycles.
U.S. Treasury yields are near multi-decade highs.
That means financing large infrastructure projects is expensive.
Companies must therefore generate higher returns to justify investment.
This creates another tension:
AI demand encourages more infrastructure spending.
But:
High interest rates increase the cost of financing that infrastructure.
Read U.S. 10-Year Yield Back Above 5%: Why Strong Growth Is Now a Risk for Stocks for the broader bond-market implications.
AI Stocks Have Already Passed the First Test
Despite rising yields, AI-related equities have remained remarkably resilient.
That suggests investors still believe AI earnings growth can overcome the higher cost of capital.
But the next phase may be more demanding.
Investors may increasingly ask:
Which companies own valuable AI infrastructure?
Which companies generate cash from it?
Which companies depend heavily on debt?
Which companies have reliable electricity access?
Which companies can scale without destroying returns?
That could produce a much wider dispersion between AI winners and losers.
Read AI Stocks Keep Rising While Bond Yields Hit Multi-Decade Highs: Is the Stock Market Becoming Too Dependent on AI? for the equity-market side of this debate.
India Could Become an Important AI Infrastructure Market
India has several characteristics that could make it increasingly important in the AI infrastructure cycle:
- enormous digital population
- rapid cloud adoption
- expanding data-centre market
- growing electricity demand
- large technology-services industry
- increasing semiconductor ambitions
AI inference could become particularly important.
If hundreds of millions of Indian consumers eventually interact regularly with AI assistants, the computing requirement could be enormous.
That creates potential demand for:
local data centres + cloud capacity + fibre networks + electricity infrastructure.
This could gradually make AI infrastructure an important component of India's digital investment story.
AI Could Transform Electricity Demand
The most underappreciated part of the AI boom may ultimately be electricity.
For decades, electricity demand in many developed economies grew slowly.
AI could change that.
Data centres require continuous power.
They also require reliable power.
Interruptions can be extremely costly.
That means technology companies increasingly care about:
- grid reliability
- generation capacity
- long-term power contracts
- renewable energy
- nuclear energy
- battery storage
- natural gas generation
The AI investment cycle could therefore eventually influence energy markets almost as much as technology markets.
The Next AI Trade May Look Very Different
The first AI trade was relatively obvious:
Buy semiconductor companies.
The next phase could be much broader.
Investors may increasingly examine:
Data-centre operators
Companies owning or developing computing facilities.
Power generators
Businesses supplying electricity to AI infrastructure.
Grid equipment
Companies manufacturing transformers, switchgear and transmission equipment.
Cooling infrastructure
AI servers produce enormous amounts of heat.
Optical networking
Large AI clusters need extremely fast data transfer.
Memory
Inference and training require huge amounts of high-speed memory.
The AI ecosystem is expanding outward.
Three Scenarios for the AI Infrastructure Boom
Scenario 1: AI Demand Keeps Accelerating
Consumer and enterprise adoption continues growing rapidly.
AI-agent usage expands.
Inference demand rises.
Data-centre utilisation remains high.
Under this scenario, infrastructure investment could continue for years.
Scenario 2: AI Grows, but Investors Become More Selective
AI adoption remains strong, but markets demand proof of profitability.
Capital remains available for companies with real contracts and cash flow.
Companies relying primarily on AI hype struggle to raise money.
This could create a healthier but more selective investment cycle.
Scenario 3: Infrastructure Gets Ahead of Demand
Companies build too much capacity.
AI revenue fails to grow quickly enough.
Data-centre utilisation disappoints.
Financing costs remain high.
Investment slows sharply.
This is the key downside risk.
What Investors Should Watch Next
The next phase of the AI boom may require monitoring a completely different set of indicators.
Watch:
- AI infrastructure fundraising
- hyperscaler capital expenditure
- data-centre construction
- electricity demand
- power prices
- grid investment
- HBM demand
- semiconductor equipment orders
- optical networking demand
- cloud revenue
- AI inference volumes
- AI revenue versus capital expenditure
- corporate debt linked to AI projects
These indicators could reveal whether AI is developing into a sustainable infrastructure cycle—or an investment boom running ahead of revenue.
The Bigger Picture: AI Is Becoming an Infrastructure Story
Artificial intelligence began as a software story.
Then it became a semiconductor story.
Now it is rapidly becoming an infrastructure story.
The latest $125.8 billion raised by Asia-Pacific high-technology companies shows how quickly that transformation is happening.
The next phase of AI may require enormous investment in:
chips
↓
data centres
↓
networking
↓
electricity
↓
power grids
The most important constraint on AI may therefore eventually be something surprisingly old-fashioned:
physical infrastructure.
And that could dramatically broaden the AI investment landscape.
The question investors should increasingly ask is no longer simply:
“Which AI stock will win?”
It is:
“Who will build—and power—the infrastructure required to run the AI economy?”
That could become one of the defining global investment themes heading into 2027.
Related LiveWorldMarket Analysis
China's Economy Is Splitting in Two: AI Profits Are Surging While Traditional Industries Struggle
AI Agents Are Becoming the New Catalyst for Chip Stocks
AI Stocks Keep Rising While Bond Yields Hit Multi-Decade Highs
U.S. 10-Year Yield Back Above 5%: Why Strong Growth Is Now a Risk for Stocks
Trump-Xi Meeting Could Be the Next Big Catalyst for AI and Semiconductor Stocks
Disclaimer: This article is for informational and educational purposes only. It does not constitute investment advice or a recommendation to buy or sell any security. AI investment, capital expenditure, interest rates and financial markets can change rapidly.
Comments (0)
Be the first to comment.
About the author
NISM-Series-X-A Investment Adviser Level 1 examination completed
Amit writes about Indian equity markets, technical analysis, macro themes and the day-to-day mechanics of trading, with a focus on making the flow of global markets legible for retail investors. He has completed the NISM-Series-X-A Investment Adviser Level 1 examination.
You May Also Like
China Exports Surge 36.3%, PPI Hits 5%: Stock Winners & Losers
Geopolitics & Trade · Oct 14, 2026 · 11 min read
China's Exports Surge 36.3% as Factory Inflation Hits 5%: Which Global Stocks Could Win or Lose? China's factories are shipping more goods overseas than expected, but a sharp rise in producer prices is raising a new question about the profitability of the world's manufacturing powerhouse. Official data released on October 14 showed that China's exports surged 36.3%…
Read more...
CXMT DRAM Breakthrough: Samsung, SK Hynix & Micron at Risk?
Technology & Sectors · Oct 13, 2026 · 11 min read
Review City PlansChina's CXMT DRAM Breakthrough: Could a Memory Price War Threaten Samsung, SK Hynix and Micron? The global semiconductor industry is confronting a new question: Could China's progress in memory-chip technology eventually undermine the pricing power of the world's largest DRAM manufacturers? Chinese chipmaker ChangXin Memory Technologies (CXMT) has reportedly made progress in a…
Read more...
RBI Dollar Window: Can Rupee Near ₹97 Survive $100 Oil?
Central Banks & Rates · Oct 12, 2026 · 9 min read
RBI Opens Special Dollar Window as Rupee Nears ₹97: Can India Protect Its Stock Market From $100 Oil? India's central bank has introduced a new defense against rupee weakness at a time when crude oil prices remain above $100 per barrel. The Reserve Bank of India (RBI) has announced a special dollar facility for three government-owned oil marketing companies, beginning October…
Read more...
Firmus $5B IPO Cancelled: AI Data Center Valuations at Risk
Technology & Sectors · Oct 11, 2026 · 9 min read
Nvidia-Backed Firmus Cancels $5 Billion IPO: Is Wall Street Finally Questioning AI Data Center Valuations? The global artificial intelligence investment boom has encountered a revealing reality check. Firmus Technologies, an Australian AI data center developer backed by Nvidia, has withdrawn its planned multibillion-dollar stock market listing after struggling to attract…
Read more...Source Parts
Starlink $8B Spectrum Deal: Telecom Stocks Fall, Towers Rise
Technology & Sectors · Oct 10, 2026 · 10 min read
Starlink's $8 Billion Spectrum Deal: Why Telecom Stocks Fell While Tower Shares Surged A single spectrum deal has sent shockwaves through the global telecommunications industry. On October 8, SpaceX announced an agreement to acquire nationwide 800 MHz wireless spectrum from Grain Management, marking a significant step toward expanding its Starlink Mobile business. The…
Read more...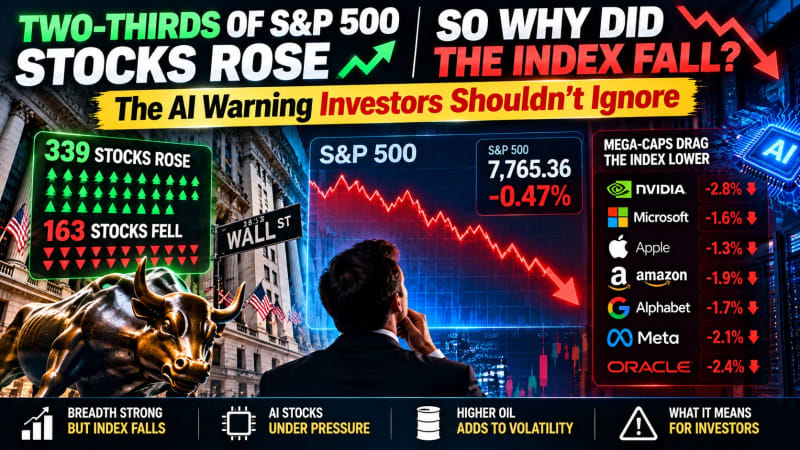
Two-Thirds of S&P 500 Stocks Rose—Why Did the Index Fall? AI Warning
Technology & Sectors · Oct 9, 2026 · 11 min read
The AI Boom Is Turning Into a $100 Billion Debt Race: Could Borrowing Costs Become the Next Risk for Tech Stocks? For the past three years, artificial intelligence has been one of the biggest forces driving global stock markets. From Nvidia's extraordinary rise to the massive expansion of AI data centres, investors have rewarded companies promising to build the infrastructure…
Read more...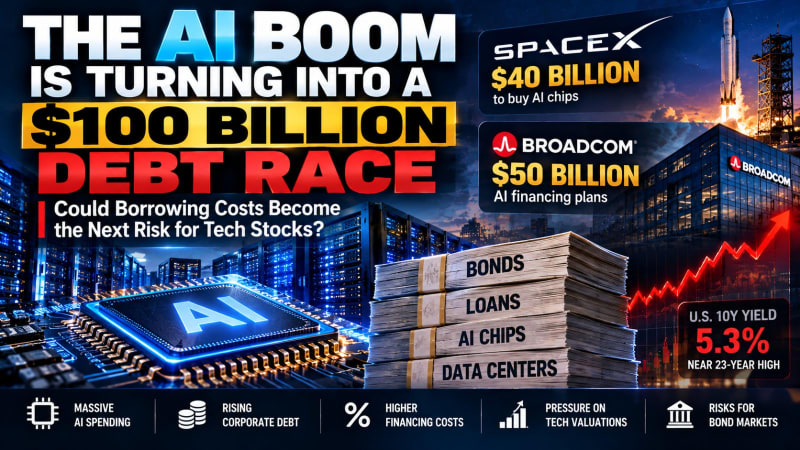
AI Debt Boom 2026: Could Borrowing Costs Hit Tech Stocks?
News · Oct 8, 2026 · 11 min read
Start InvestingThe AI Boom Is Turning Into a $100 Billion Debt Race: Could Borrowing Costs Become the Next Risk for Tech Stocks? For the past three years, artificial intelligence has been one of the biggest forces driving global stock markets. From Nvidia's extraordinary rise to the massive expansion of AI data centres, investors have rewarded companies promising to build the infrastructure…
Read more...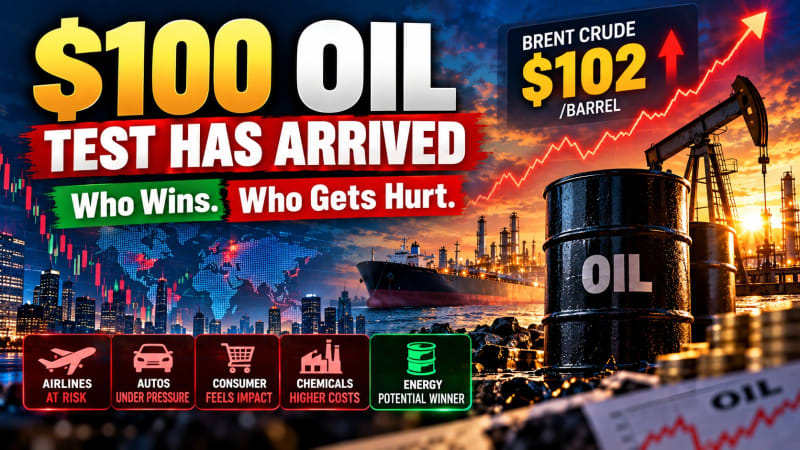
$100 Oil Is Back: Which Stock Markets and Sectors Are Most Exposed?
Commodities & Energy · Oct 7, 2026 · 12 min read
The $100 Oil Test Has Arrived: Which Global Stock Markets and Sectors Are Most Exposed If Crude Stays Above Triple Digits? Oil above $100 is no longer a hypothetical risk for global markets. Brent crude traded above $101 a barrel on October 7, while U.S. West Texas Intermediate hovered near $90 as investors confronted a combination of Middle East supply risks, attacks on…
Read more...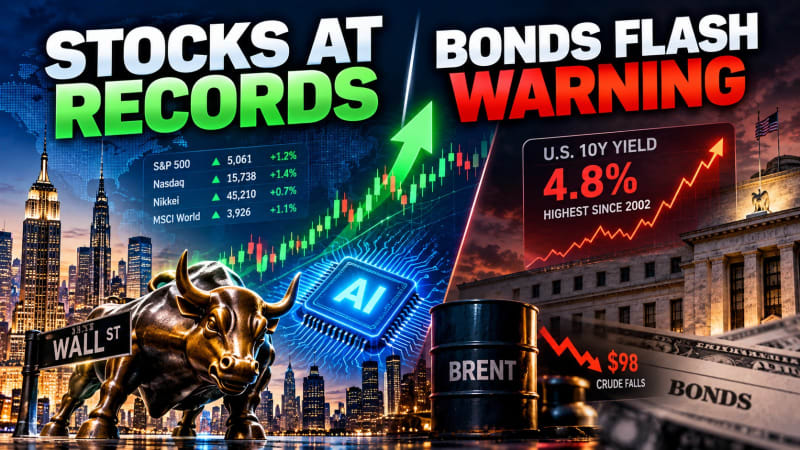
Stocks Hit Record Highs While Bond Yields Flash a Warning: Which Market Is Right?
Global Markets & Economy · Oct 6, 2026 · 9 min read
Invest in StocksStocks Are Hitting Records While Bonds Flash a Warning: Which Market Is Right? Something unusual is happening across global financial markets. Stocks are celebrating. Bonds are warning. On October 6, global equities climbed to their highest level in roughly two weeks. The S&P 500 reached another record, while the technology-heavy Nasdaq extended its run of all-time highs. The…
Read more...
France Bond Spread Hits 2011-Era Extreme: Is Europe’s Debt Risk Returning?
Global Markets & Economy · Oct 6, 2026 · 9 min read
France’s Bond Spread Just Hit a 2011-Era Extreme: Is Europe Quietly Re-Entering a Sovereign-Debt Risk Trade? For much of 2026, investors have been focused on the Federal Reserve, oil, inflation and the extraordinary resilience of AI-driven equity markets. But another risk is quietly emerging in Europe. The gap between France’s 10-year government bond yield and Germany’s…
Read more...