US Consumer Staples Rally 9.6%: FMCG Valuation Risk for India
US Consumer Staples Surge 9.6% as Valuations Overtake Tech: Is the Safe-Stock Trade Becoming a Trap for Indian FMCG Investors?
Something unexpected is happening on Wall Street.
As investors become increasingly cautious about expensive artificial intelligence stocks, money has been moving into an unlikely market leader: consumer staples.
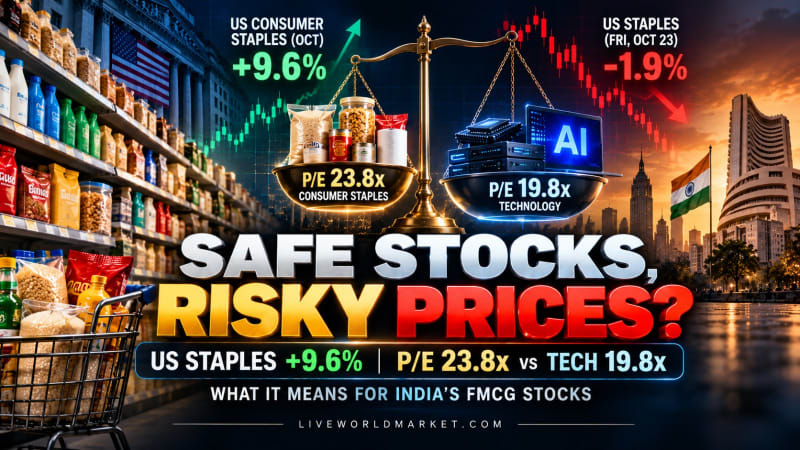
The U.S. consumer-staples sector has gained approximately 9.6% in October through October 23, putting it on course for its strongest monthly performance in 26 years.
But an even more interesting development is emerging beneath the rally.
According to FactSet data reported by MarketWatch, the S&P 500 consumer-staples sector was trading at approximately 23.8 times forward earnings on October 20, compared with just 19.8 times for the technology sector.
In other words, investors were paying more for each dollar of expected earnings from companies selling everyday consumer products than from the technology sector.
That reverses the usual assumption that defensive companies should command lower valuations because their earnings growth is typically slower.
The rally also showed signs of volatility.
On Friday, October 23, consumer staples declined approximately 1.9%, making the sector one of Wall Street's weakest performers that day.
For investors in India's fast-moving consumer goods (FMCG) sector, this creates an important question.
Could the same defensive stocks that protect portfolios during periods of uncertainty become vulnerable when investors pay too much for their predictable earnings?
The answer matters for companies such as Hindustan Unilever, Nestlé India, ITC, Britannia, Dabur, Marico and Tata Consumer Products.
The real investment risk may not be weak consumer demand alone.
It may be the combination of expensive valuations, moderate earnings growth and rising raw-material costs.
1. Why Are U.S. Consumer-Staples Stocks Suddenly Rallying?
For much of the recent global equity rally, technology and artificial intelligence dominated investor attention.
Semiconductor companies, cloud-computing businesses and AI infrastructure providers attracted substantial investment as markets anticipated years of rapid earnings growth.
However, October brought renewed concerns.
Investors began questioning the scale of AI capital expenditure, the financing costs of massive data-centre investments and how quickly AI spending would generate sustainable returns.
As technology-sector volatility increased, some investors rotated toward businesses with more predictable demand.
Consumer-staples companies manufacture or sell products such as food, beverages, household cleaning products and personal-care essentials.
Consumers generally continue buying these products during periods of economic uncertainty.
This makes the sector relatively defensive.
However, relative earnings stability does not mean that share prices cannot experience significant declines.
Global Market Snapshot: October 2026

Sources: Wall Street Journal, MarketWatch/FactSet, Reuters and Barron's. Figures refer to different explicitly dated snapshots.
The most important observation is that the defensive rally has occurred alongside concerns about the sustainability of technology valuations.
But the market may now be creating another valuation problem.
Investors moving away from expensive growth stocks could be making defensive stocks expensive instead.
For more background on the changing technology-investment environment, read AI Stocks vs. 5.2% Treasury Yields: Is the S&P 500 Too Dependent on AI?.
2. Consumer Staples Are Trading at Higher P/E Multiples Than Technology
The price-to-earnings ratio, or P/E, is one of the most widely used measures of equity valuation.
It indicates how much investors are paying for each dollar or rupee of corporate earnings.
A company trading at 30 times earnings has a market value equal to 30 times its annual earnings.
A forward P/E ratio uses expected future earnings rather than historical profits.
Higher multiples may be justified when investors anticipate strong earnings growth, stable cash flows or other desirable characteristics.
However, a high P/E ratio also increases the importance of future earnings delivery.
Why the Current U.S. Valuation Comparison Matters
At the October 20 snapshot:
- Consumer staples: 23.8× forward earnings
- Technology: 19.8× forward earnings
Consumer staples therefore carried a forward earnings multiple approximately 20% higher than the technology sector.
This does not establish that every technology company is cheaper than every consumer-staples company.
The two sector indices contain different businesses, growth profiles and index weightings.
Nevertheless, it is a significant change in how investors are valuing the sectors.
Traditionally, consumer-staples companies have attracted investors seeking earnings resilience and dividends rather than exceptional earnings growth.
Technology companies have often attracted higher valuations because of stronger expected long-term growth.
When defensive-sector valuations exceed technology-sector multiples, the market is placing an unusually high value on earnings stability.
The risk emerges when that stability is already reflected in the share price.
A defensive company does not need to report falling profits for its stock to decline.
Its valuation can fall simply because investors become less willing to pay a large premium for those profits.
3. The Hidden Risk: Safe Businesses Are Not Always Safe Investments
One of the most important distinctions in equity investing is the difference between business quality and investment value.
A company can operate an excellent business while its shares deliver disappointing returns.
Consider a consumer-products manufacturer with trusted brands, recurring customer demand and consistent earnings growth.
Those characteristics make the business attractive.
But what happens if its shares are already priced for years of strong performance?
Even a modest disappointment may trigger a valuation correction.
The financial impact can be meaningful.
Illustrative Valuation Risk
Assume an FMCG company's shares trade at 40 times expected annual earnings.
Over the following year, earnings per share increase by 10%.
Despite that improvement, the market reduces the P/E multiple because investors are no longer willing to pay the same premium.

Assumptions: Initial P/E of 40×, no dividends, and the same underlying earnings measure throughout. This is a hypothetical mathematical illustration, not a stock forecast.
The example demonstrates an important principle.
A company can grow earnings by 10% while its share price falls 12% if its valuation multiple contracts sufficiently.
This is the hidden danger of paying very high valuations for relatively predictable businesses.
Investors may be correct about the company's long-term strength but still experience poor returns because the initial purchase price was excessive.
4. Could the Same Risk Be Developing in India's FMCG Sector?
India's FMCG market has different characteristics from the United States.
It benefits from a large consumer base, increasing formalisation, growing distribution networks and opportunities to expand branded-product penetration.
Indian FMCG companies may also benefit from rising household incomes, rural market development and premiumisation.
These structural factors help explain why some leading Indian consumer businesses command relatively high valuation multiples.
But long-term growth opportunities do not eliminate valuation risk.
For Indian investors, the critical issue is whether the price paid for a company's shares is justified by its future earnings growth.
Consider a mature FMCG company with strong brands but modest volume growth.
If its shares already trade at an elevated multiple, investors are depending on several favourable conditions.
Revenue must continue growing.
Operating margins must remain stable or improve.
Market share must be protected.
And the company's valuation premium must remain broadly intact.
If any of these assumptions disappoint, share-price performance can weaken.
The current U.S. experience provides an important lesson.
A defensive-sector rally can become a valuation risk if investors begin paying increasingly high prices for relatively slow-growing earnings.
However, India's FMCG valuations should be assessed using company-specific data and Indian historical valuation ranges, not by directly applying the U.S. sector P/E ratios.
Investors can follow domestic sector performance through the LiveWorldMarket India Stock Market Dashboard, including the Nifty FMCG sector.
5. India's FMCG Companies Face a Second Problem: Input-Cost Inflation
Valuation is only part of the story.
Indian FMCG companies are also facing renewed pressure from raw-material inflation.
Recent industry reports highlight higher costs for sugar, edible oils, packaging materials, agricultural commodities and petroleum-derived inputs.
The increase in crude oil prices creates additional complications because many FMCG products rely on packaging, logistics and manufacturing inputs affected by energy costs.
These pressures have become more significant as companies attempt to balance profitability with affordability.
Price increases can protect margins, but excessive increases may cause price-sensitive consumers to reduce purchases or switch to cheaper alternatives.
Recent industry analysis has suggested that operating margins could come under pressure during the second half of FY2026–27.
Indian FMCG Cost Exposure

Actual exposure and pricing power vary considerably by company and product category.
The risk is especially relevant for companies operating in highly competitive, price-sensitive categories.
If input costs rise rapidly, manufacturers may need to choose between protecting margins and preserving sales volumes.
That trade-off matters greatly when stock valuations already reflect high expectations.
6. Nestlé India Provides a Real Example of the Earnings-Valuation Disconnect
One of the clearest recent examples comes from Nestlé India.
On October 15, the company reported a 36% year-on-year increase in quarterly net profit to approximately ₹1,027 crore.
Revenue increased around 20% to ₹6,788 crore, supported by resilient demand for products including Maggi and Nescafé.
Sales volumes also grew at a double-digit pace.
On the surface, these were strong financial results.
Yet the stock declined approximately 9% following the announcement.
Why?
Investors were concerned about the outlook for future growth, higher commodity costs and whether the results sufficiently exceeded expectations.
The company also highlighted challenges from food inflation and rising input costs.
This illustrates a crucial investment principle.
Strong earnings growth does not automatically produce positive share-price performance when market expectations are already demanding.
The relevant comparison is not only between current profits and last year's profits.
It is between actual results, expected results and the valuation investors are willing to assign to future earnings.
For Indian FMCG investors, that makes earnings expectations just as important as headline profit growth.
7. Which Indian FMCG Stocks Should Investors Monitor?
The latest U.S. valuation shift provides a useful framework for examining Indian consumer businesses.
However, individual companies should not be grouped together simply because they operate in the FMCG sector.
Their products, market positions, commodity exposure and growth opportunities differ.
Indian FMCG Research Watchlist

Research watchlist only. This is not a ranking, buy recommendation or assessment of current share-price attractiveness.
Different companies may experience the same economic conditions very differently.
A premium consumer brand may have greater ability to raise prices.
A mass-market manufacturer may depend more heavily on affordable pack sizes.
A company with efficient procurement could absorb cost increases more effectively than competitors.
For investors, the objective should be to distinguish sustainable earnings growth from growth driven mainly by temporary pricing effects.
8. Rural and Urban Demand: Another Important Variable
India's FMCG growth depends heavily on both rural and urban consumption.
Rural households represent a substantial market for everyday consumer products, particularly affordable packaged foods, personal care and household essentials.
Urban markets provide opportunities for premium brands, modern retail, convenience products and online distribution.
During recent quarters, rural demand has often outperformed urban demand, although the gap has narrowed.
Industry data reported for the September quarter indicate that some categories of rural packaged-food sales experienced strong value growth.
However, value growth is not the same as volume growth.
For example, a company may report 10% revenue growth because product prices increased, even though unit sales remain unchanged.
That distinction becomes especially important during periods of inflation.
A healthy consumer recovery is generally more encouraging when higher sales are supported by genuine increases in consumption rather than price increases alone.
Investors should therefore examine three variables separately.
Volume growth: Are consumers buying more products?
Price growth: Is revenue increasing primarily because products have become more expensive?
Product mix: Are customers shifting toward premium products or lower-priced alternatives?
This analysis can help reveal whether an FMCG company's earnings growth is sustainable.
9. Why Friday's U.S. Staples Selloff Matters
The October rally has been impressive, but Friday's trading showed why defensive stocks should not be treated as risk-free.
On October 23, U.S. consumer staples declined approximately 1.9%.
The sector had risen approximately 3.1% in the preceding session.
This rapid reversal is noteworthy because investors typically associate consumer staples with lower earnings cyclicality and relatively stable market performance.
But strong buying activity can leave even defensive sectors vulnerable to sudden profit-taking.
Several forces may contribute to these reversals.
Investors may reduce crowded defensive positions.
Short-term traders may lock in gains.
Technology shares may recover, encouraging rotation back toward growth sectors.
And rising interest rates or changing inflation expectations may alter the relative attractiveness of defensive businesses.
However, Friday's decline alone does not establish that the consumer-staples rally has ended.
It illustrates that defensive earnings characteristics do not guarantee defensive share-price movements, especially after a rapid rise in valuations.
10. Five Indicators Indian FMCG Investors Should Track
Rather than assuming that FMCG stocks are automatically attractive during global uncertainty, investors should evaluate a combination of valuation, growth and profitability indicators.
FMCG Investment Checklist

A high-quality FMCG business may still deserve a valuation premium.
The important question is how large that premium should be relative to expected earnings growth, competitive strength and financial risk.
A company delivering strong volume growth, healthy cash generation and improving profitability may justify a different valuation from one relying primarily on price increases to support revenues.
11. Three Scenarios for Indian FMCG Stocks
The direction of India's consumer sector will depend on demand trends, commodity costs, earnings performance and broader equity-market valuations.
Scenario 1: Demand Improves and Input Inflation Eases
Rural and urban consumption strengthen.
Raw-material prices stabilise.
FMCG companies deliver healthy volume growth and maintain margins.
Under these conditions, premium valuations may remain supported by improving business fundamentals.
Scenario 2: Sales Rise but Earnings Growth Disappoints
Revenue increases because companies raise prices.
However, volumes remain weak and raw-material costs stay elevated.
Operating margins fail to improve significantly.
In this scenario, businesses trading at expensive valuations could become vulnerable to earnings downgrades and P/E compression.
Scenario 3: Global Investors Rotate Back Toward Growth
Technology-sector volatility subsides.
Investors become more confident about AI earnings and capital expenditure.
Demand for defensive investments moderates.
Even if FMCG companies continue reporting stable earnings, share prices could weaken if investors reduce the premium they are willing to pay for predictable cash flows.
These scenarios are illustrative, not predictions.
The central lesson is that share-price performance depends on both earnings and valuation.
12. LiveWorldMarket Insight: The Real Risk Is Paying Too Much for Safety
The most important development in the U.S. consumer-staples rally is not simply its magnitude.
It is the message it sends about investor behaviour.
Markets sometimes move from one popular investment theme to another.
When artificial intelligence dominates market performance, investors may become concerned about excessive technology valuations.
As technology volatility rises, defensive companies become attractive.
But if too much money moves into defensive stocks, their valuations can also become stretched.
The original objective of reducing portfolio risk may then create a different form of exposure: valuation risk.
This is particularly important for Indian FMCG stocks because investors have historically assigned meaningful premiums to companies with strong brands, established distribution networks and predictable earnings.
Those strengths remain valuable.
However, they should not be considered independently of the price paid for them.
A strong brand does not guarantee high future shareholder returns.
A reliable business does not eliminate the possibility of a significant stock-market correction.
And stable consumption does not prevent earnings disappointment when input costs rise.
The distinction investors must make is between buying a high-quality company and buying that company at an attractive valuation.
For a broader view of changing global market sentiment, visit What Changed While You Slept?.
13. Final Takeaway: Is the Safe-Stock Trade Becoming a Trap?
The U.S. consumer-staples sector's approximately 9.6% October rally highlights a significant rotation away from some growth-oriented investments.
At the same time, its elevated forward earnings multiple raises an important question about valuation discipline.
A sector known for relatively stable demand was trading at a higher forward P/E ratio than technology in the October 20 snapshot.
That does not mean every consumer-staples stock is overvalued or that technology stocks are universally attractive.
It means the market is assigning an unusually high premium to certain defensive earnings streams.
For Indian investors, the lesson is particularly relevant.
FMCG companies with strong brands, healthy cash generation and durable competitive positions can remain attractive long-term businesses.
But their investment returns will depend on earnings growth, margins, market expectations and purchase valuations.
Rising raw-material costs and uneven consumer demand add another layer of uncertainty.
The biggest risk may not be that defensive businesses suddenly become weak. It may be that investors pay prices that leave too little room for disappointment.
In equity markets, safety is not determined by the sector label alone.
It also depends on the valuation.
Frequently Asked Questions
Why have U.S. consumer-staples stocks rallied in October 2026?
Investors have shifted toward businesses with relatively stable consumer demand amid technology-sector volatility, concerns about AI investment and uncertainty over future economic growth.
Are consumer-staples stocks more expensive than technology stocks?
According to FactSet data reported on October 20, 2026, the S&P 500 consumer-staples sector traded at approximately 23.8 times forward earnings, compared with 19.8 times for the technology sector. These are dated sector-level averages, not valuations for every company.
Are Indian FMCG stocks safe during market corrections?
FMCG businesses may experience relatively stable demand, but their share prices can still fall because of expensive valuations, earnings disappointments, higher input costs or changing investor preferences.
Which Indian FMCG stocks should investors track?
Investors can research Hindustan Unilever, Nestlé India, Britannia, ITC, Dabur, Marico and Tata Consumer Products, among others. Company-specific valuation and financial performance should guide the analysis.
Can FMCG shares fall even when earnings increase?
Yes. If the market reduces the valuation multiple assigned to a company, its share price may decline even when earnings per share increase.
What is the most important metric for FMCG investors?
No single metric is sufficient. Investors should examine volume growth, pricing power, gross margins, cash flow, earnings revisions and valuation together.
Sources and References
- Wall Street Journal — U.S. Stocks Fall as Oil Prices Hit Five-Month High — October 23, 2026.
- MarketWatch — Investors' Search for Safety Has Made Toothpaste Stocks More Expensive Than Tech — October 20, 2026.
- Reuters — U.S. Shares Close Lower as Technology Stabilises — October 23, 2026.
- Reuters — Nestlé India Flags Commodity Inflation After Profit Surges 36% — October 15, 2026.
- Business Standard — FMCG Companies Grapple With Cost Inflation and Margin Pressure — October 18, 2026.
- Financial Express — FMCG Rural–Urban Consumption Trends — October 2026.
Data note: October's 9.6% U.S. consumer-staples return refers to month-to-date performance through October 23, not a single-day gain or a completed calendar-month return. Forward P/E ratios reflect the October 20 snapshot and may change.
Disclaimer: This article is for educational and informational purposes only. It does not constitute investment advice or a recommendation to buy, hold or sell securities. Historical returns, valuation multiples and illustrative examples do not guarantee future performance. Readers should perform independent research and consult an appropriately registered investment adviser when required.
Comments (0)
Be the first to comment.
About the author
NISM-Series-X-A Investment Adviser Level 1 examination completed
Amit writes about Indian equity markets, technical analysis, macro themes and the day-to-day mechanics of trading, with a focus on making the flow of global markets legible for retail investors. He has completed the NISM-Series-X-A Investment Adviser Level 1 examination.
You May Also Like
SpaceX 80,000 Cell Sites: Will Starlink Challenge Jio & Airtel?
Global Markets & Economy · Oct 24, 2026 · 17 min read
SpaceX's 80,000 Cell-Site Plan Sends US Telecom Stocks Down 8%: Could Starlink Disrupt Jio and Airtel Next? A major shift may be emerging in the global telecommunications industry—and Wall Street has already started reacting. Shares of American telecommunications giants AT&T and T-Mobile plunged nearly 8% on October 23 after reports revealed that Elon Musk's SpaceX was…
Read more...
US 10-Year Treasury Yield Below 5%: Growth Shock Warning?
Central Banks & Rates · Oct 23, 2026 · 17 min read
US 10-Year Treasury Yield Falls Below 5% Despite $114 Oil: Is the Bond Market Warning of a Global Growth Shock? Something unusual is happening across global financial markets. The yield on the benchmark U.S. 10-year Treasury has fallen sharply below the psychologically important 5% level, even as Brent crude oil has surged toward $114 per barrel and technology stocks have…
Read more...
Brent Crude Tops $110: Impact on Indian Stocks & Earnings
Global Markets & Economy · Oct 22, 2026 · 14 min read
Brent Crude Tops $110: Why Indian Airlines, Paints and Tyre Stocks Face a Hidden Earnings Risk Brent crude oil has climbed above $110 per barrel, intensifying concerns that rising global energy prices could squeeze corporate profit margins, increase India's import costs and create further volatility in domestic equities. On October 22, Brent futures traded above $111 after…
Read more...
India Optical Fibre Exports Jump 158%: AI's Hidden Winners
Global Markets & Economy · Oct 21, 2026 · 12 min read
India's Optical Fibre Exports Jump 158% as Japan's Chip Shipments Surge 49%: The Hidden Winners of the AI Infrastructure Boom Artificial intelligence may be transforming the technology industry, but some of its most important economic beneficiaries are not necessarily the companies developing AI models. They may be the businesses manufacturing the physical infrastructure that…
Read more...
Nasdaq Rises 1.1%, KOSPI Falls 3.6%: AI Stocks and India Impact
Global Markets & Economy · Oct 20, 2026 · 12 min read
Nasdaq Jumps 1.1% but KOSPI Crashes Over 3%: Why the AI Stock Rebound Is Failing in Asia—and What It Means for India Global technology stocks are sending conflicting signals. On Monday, October 19, the Nasdaq Composite gained 1.11%, recovering part of the losses suffered during the previous week's technology selloff. U.S. semiconductor stocks also rebounded, with the…
Read more...
Jio IPO 2026: $108 Billion Valuation Amid Global AI Selloff
Market Valuation & Behaviour · Oct 19, 2026 · 14 min read
Jio IPO at $108 Billion Amid Global AI Stock Selloff: Can India's Biggest IPO Defy the Tech Market Rout? India is preparing for what could become its largest-ever initial public offering at a time when global investors are reassessing technology valuations, artificial intelligence spending and the financial sustainability of digital infrastructure. Jio Platforms, the digital…
Read more...
China GDP Grows 4.5% as Oil Falls: Can India Stocks Benefit?
Global Markets & Economy · Oct 19, 2026 · 12 min read
China GDP Grows 4.5% as Oil Falls Toward $108: Could India and Asian Stocks Benefit From a Global Market Reset? China's economy expanded faster than expected in the third quarter of 2026, but the latest economic data reveals a growing divide between its powerful export industries and weak domestic demand. At the same time, global crude oil prices declined toward $108 per…
Read more...
STOXX 600 Rises 2% as Nasdaq Falls 4.5%: Is Europe Taking the Lead?
Global Markets & Economy · Oct 18, 2026 · 13 min read
Europe’s STOXX 600 Gains Over 2% as Nasdaq Falls 4.5%: Is Global Stock Market Leadership Shifting? Europe's stock markets delivered their strongest week since June while U.S. technology shares suffered their worst weekly decline in months. The divergence raises a critical question for global investors: Is the market beginning to reward diversified earnings growth instead of…
Read more...
CoreWeave Bond Yields Hit 16%: AI Data Center Debt Risks
Technology & Sectors · Oct 17, 2026 · 13 min read
CoreWeave Bond Yields Hit 16%: Is AI Data-Center Debt Becoming the Next Big Risk for Global Stocks? The artificial intelligence boom has entered a new phase. Investors are no longer asking only how much money AI companies can earn. They are increasingly questioning how much it costs to finance the infrastructure supporting that growth. This week, CoreWeave, a U.S.-based AI…
Read more...
Indonesia Stocks Crash 11.57%: Will MSCI Downgrade Benefit India?
India & Global Connections · Oct 16, 2026 · 12 min read
Indonesia Stocks Plunge 11% as MSCI Proposes Downgrade: Could India and Other Emerging Markets Benefit? Indonesia's stock market has suffered its sharpest one-day decline in nearly three decades, but the bigger story extends far beyond Jakarta. A proposed MSCI downgrade could eventually force global index funds to remove Indonesian equities from their portfolios, potentially…
Read more...