$100 Oil Is Back: Which Stock Markets and Sectors Are Most Exposed?
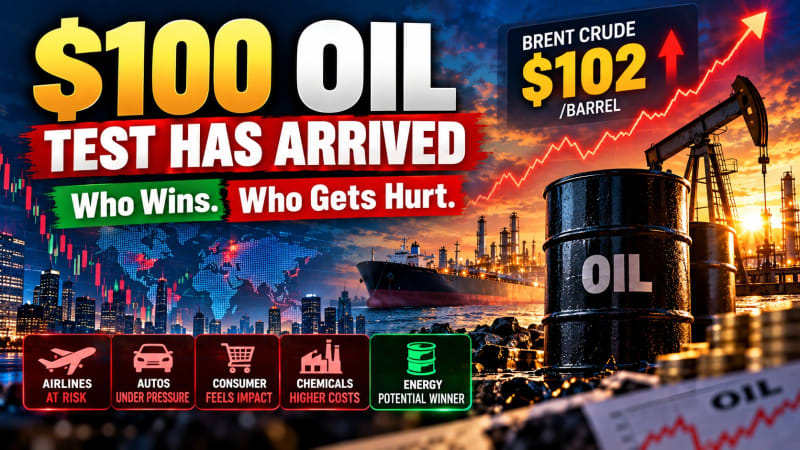
The $100 Oil Test Has Arrived: Which Global Stock Markets and Sectors Are Most Exposed If Crude Stays Above Triple Digits?
Oil above $100 is no longer a hypothetical risk for global markets.
Brent crude traded above $101 a barrel on October 7, while U.S. West Texas Intermediate hovered near $90 as investors confronted a combination of Middle East supply risks, attacks on energy infrastructure and a storm threatening oil-producing regions in the Gulf of Mexico.
The latest U.S. inventory data added another complication: crude inventories unexpectedly fell by 3.2 million barrels in the week ended October 2.
But the most important question for investors is no longer whether oil can cross $100.
It already has.
The real question is:
What happens to global stock markets if crude stays above $100 for weeks or months rather than days?
That distinction matters enormously.
A short-lived geopolitical spike can be absorbed by financial markets.
A sustained period of triple-digit oil can affect inflation, interest rates, currencies, corporate margins, consumer spending and ultimately equity valuations.
And the impact will not be distributed equally.
Some markets and sectors could face significant pressure.
Others could actually benefit.
Why $100 Oil Matters More Now
Oil is rising at an unusually difficult moment for the global economy.
Long-term government bond yields are already elevated.
Central banks are still fighting inflation.
Governments are dealing with large fiscal deficits.
And many global stock markets entered October with expensive valuations after powerful rallies led by artificial intelligence and technology shares.
That means the global economy has less room to absorb another inflation shock.
The transmission mechanism is straightforward:
Oil above $100
↓
Transportation and production costs rise
↓
Inflation remains elevated
↓
Central banks keep interest rates higher
↓
Bond yields remain under pressure
↓
Corporate financing becomes more expensive
↓
Equity valuation multiples face pressure
The oil market therefore has the potential to connect several risks investors have recently been treating separately.
Global Stocks Are Already Reacting
The first signs are visible.
On October 7, the MSCI global equity index fell roughly 0.9%, while Europe's STOXX 600 declined around 1.1% during the session.
In the United States, the S&P 500 dropped around 0.6% and the Nasdaq around 0.85%, only a day after both indices reached fresh records.
The reason isn't oil alone.
Investors are simultaneously dealing with high bond yields, European fiscal concerns and uncertainty about the path of monetary policy.
But Brent above $100 adds another problem:
Inflation could become harder to bring down.
That matters because long-dated U.S. Treasury yields are already around their highest levels in more than two decades.
Oil doesn't need to cause a recession to hurt equities.
It only needs to convince investors that interest rates may have to remain higher for longer.
Which Stock Markets Are Most Exposed?
The impact of $100 oil depends heavily on whether a country is a major energy importer or exporter.
1. India — Among the Most Important Markets to Watch
India deserves particular attention.
The country imports most of the crude oil it consumes, making higher international energy prices relevant to inflation, the trade balance, the rupee and corporate margins.
That pressure became particularly visible on October 7.
The Reserve Bank of India raised its repo rate by 25 basis points to 5.50%, its first increase since 2023, and shifted its policy stance toward “calibrated tightening.”
The Nifty 50 subsequently closed 0.76% lower, while the Sensex declined 0.59%.
Rate-sensitive sectors suffered more.
Real estate fell around 1.8%, autos about 1.6%, and FMCG approximately 0.9%.
The rupee also weakened toward its record low.
If oil remains above $100, India faces a difficult combination:
Higher crude import bill
Inflation pressure
Rupee weakness
Higher interest rates
Potential foreign portfolio outflows
That doesn't mean the entire Indian stock market must fall.
But it changes which sectors investors may favour.
Track the India Stock Market Dashboard
2. Europe — Energy Shock Meets Fiscal Stress
Europe faces a different version of the same problem.
The region is already dealing with elevated borrowing costs and renewed concerns about government finances, particularly in France.
Now higher energy prices are adding another inflationary variable.
European stocks retreated on October 7 as both oil prices and government bond yields moved higher.
This matters because Europe remains particularly sensitive to imported energy costs.
Higher energy prices can affect:
- Industrial production
- Chemicals
- Transportation
- Consumer spending
- Corporate margins
- Inflation
- ECB policy
Europe therefore faces a potentially uncomfortable combination:
Higher energy costs + weak growth + fiscal stress + restrictive interest rates.
That could make sustained $100 oil more problematic for European equities than a temporary geopolitical spike.
Related Insight: France’s Bond Spread Just Hit a 2011-Era Extreme: Is Europe Quietly Re-Entering a Sovereign-Debt Risk Trade?
3. Japan — Oil Plus a Weak Currency
Japan has another vulnerability.
Japan imports large amounts of energy, meaning a rise in dollar-denominated oil prices can increase domestic costs.
Currency movements amplify the problem.
If the yen remains weak while oil stays above $100, Japanese companies effectively face two pressures:
Higher global oil prices
and
More expensive dollar-denominated imports.
That can create difficulties for transport companies, utilities and businesses unable to pass higher input costs to consumers.
However, Japanese exporters can simultaneously benefit from a weaker currency.
The result is likely to be substantial sector divergence rather than a simple bearish outcome for the entire Japanese market.
4. United States — Less Vulnerable, But Not Immune
The United States is in a different position because it is one of the world's largest oil producers.
That provides a natural cushion.
Higher oil prices can improve revenues and cash flows for U.S. energy companies.
Indeed, energy was one of the few S&P 500 sectors trading higher as the broader U.S. market declined on October 7.
But the wider stock market is not immune.
The bigger U.S. risk comes through inflation and interest rates.
If $100+ oil keeps headline inflation elevated, investors may have to reconsider how quickly monetary policy can become less restrictive.
That becomes especially important when long-term Treasury yields are already at levels last seen more than two decades ago.
For expensive technology stocks, the equation becomes:
Higher oil → higher inflation → higher yields → higher discount rates → pressure on valuations.
This is why even an energy-independent economy can experience equity-market consequences from an oil shock.
Follow the U.S. Stock Market Dashboard
5. Oil-Producing Markets Could Be Relative Winners
Not every country loses from higher oil.
Major energy exporters can benefit from increased export revenues and stronger government finances.
That potentially gives markets in energy-producing economies an advantage over large oil-importing countries.
But even here there is an important caveat.
Geopolitical escalation can overwhelm the financial benefit of higher oil.
That is already visible in parts of the Middle East.
On October 7, Saudi Arabia's main stock index fell roughly 0.5%, while markets in Dubai, Abu Dhabi and Qatar also weakened as investors responded to escalating regional tensions.
So:
Higher oil is positive for exporters.
The geopolitical event causing higher oil may not be.
That distinction matters.
Which Sectors Are Most Vulnerable to $100+ Oil?
Country exposure tells only half the story.
The bigger investment opportunities — and risks — may emerge at the sector level.
Airlines — Directly in the Firing Line
Airlines are among the most obvious losers from sustained high oil prices.
Jet fuel is a major operating expense.
When fuel prices rise sharply, airlines must either absorb the additional cost or attempt to pass it to passengers through higher fares.
Both options can create problems.
Absorbing the cost hurts margins.
Increasing ticket prices can reduce demand.
Airlines with weaker fuel hedges or lower pricing power are particularly exposed.
Logistics and Transportation — Higher Costs Everywhere
Trucking, shipping and logistics companies also face higher fuel expenses.
Some businesses can pass those costs to customers through fuel surcharges.
Others cannot.
The key variable becomes pricing power.
Companies capable of passing higher costs to customers can defend margins.
Companies operating in highly competitive industries may struggle.
Autos — A Double Hit
Automakers can face two simultaneous problems.
First, higher fuel costs can weaken demand for fuel-intensive vehicles.
Second, if higher oil contributes to inflation and central-bank tightening, vehicle financing becomes more expensive.
That creates:
Higher running costs
Higher financing costs
=
Pressure on vehicle affordability.
India's auto index falling about 1.6% following the RBI's October 7 rate increase demonstrates how quickly rate-sensitive sectors can react.
Consumer Goods — The Hidden Margin Problem
Consumer businesses can be affected indirectly.
Oil is embedded in transportation, packaging, plastics, chemicals and distribution.
That means higher crude prices can quietly move through supply chains.
Companies then face a decision:
Raise prices
or
Accept lower margins.
Businesses with strong brands and pricing power are better positioned.
Companies competing primarily on price can be more vulnerable.
Chemicals and Manufacturing — Feedstock Pressure
Oil is not merely a transportation fuel.
It is also an important industrial feedstock.
Petrochemicals are used in plastics, packaging, textiles, paints, pharmaceuticals and thousands of industrial products.
Sustained high oil can therefore increase manufacturing input costs well beyond the energy sector itself.
For energy-intensive industries, $100 oil can behave almost like an additional tax on production.
Energy — The Obvious Beneficiary?
Oil and gas producers are among the clearest potential winners.
Higher realized oil prices can increase revenue, free cash flow and potentially shareholder distributions.
But investors should distinguish between different parts of the energy industry.
Upstream producers
Generally benefit directly from higher crude prices.
Refiners
Their profitability depends heavily on refining margins rather than crude prices alone.
Oil-field services
Can benefit if higher prices encourage additional drilling and investment.
Fuel retailers
May face margin pressure if governments or consumers resist higher retail prices.
So even within energy, the $100-oil trade is not as simple as “buy everything.”
An Even Bigger Warning Is Coming From Diesel
Crude oil gets the headlines.
But refined products may be even more important for the real economy.
European benchmark diesel margins surged sharply on October 7 amid concerns about constrained refining capacity and energy infrastructure disruptions.
Diesel matters because it powers:
Trucks
Industrial machinery
Agriculture
Construction
Shipping
and large parts of the global logistics system.
If crude remains above $100 while diesel markets become even tighter, the economic impact could spread much faster through supply chains.
That is a development global equity investors should watch closely.
Why $100 Is Not the Most Important Number
Investors naturally focus on round numbers.
$100 oil sounds dramatic.
But the duration matters more than the level.
There is a major difference between:
Brent at $102 for five days
and
Brent averaging $105–$110 for three months.
The first could be a geopolitical risk premium.
The second could begin changing inflation forecasts, monetary-policy expectations, corporate earnings estimates and consumer behaviour.
That is when oil becomes a genuine macroeconomic shock.
What Happens If Oil Reaches $120?
A move toward $120 would significantly increase the stakes.
Markets would likely begin questioning whether inflation could accelerate again.
Central banks could become more cautious about easing monetary policy — or consider further tightening.
Bond yields could remain elevated.
Consumers would face higher fuel bills.
Companies would face greater input costs.
And countries heavily dependent on imported energy would experience worsening trade balances.
The potential chain becomes:
$120 oil
↓
Inflation expectations rise
↓
Rate-cut expectations disappear
↓
Bond yields rise
↓
Dollar strengthens
↓
Emerging-market currencies weaken
↓
Foreign capital becomes more selective
↓
Equity valuations compress
At that point, oil would no longer be simply a commodity-market story.
It would become one of the dominant global macro stories.
India Could Feel the Pressure Through the Rupee
For Indian investors, the currency channel deserves special attention.
Higher oil means Indian importers need more dollars to purchase crude.
That can increase demand for dollars and pressure the rupee.
The rupee fell close to its record low against the dollar on October 7.
India's foreign-exchange reserves have also declined by roughly $50 billion from their September peak, partly reflecting RBI intervention as the central bank attempts to manage currency volatility.
This creates an important feedback loop:
Oil rises
↓
Import bill rises
↓
Dollar demand increases
↓
Rupee weakens
↓
Imported oil becomes even more expensive in rupee terms
↓
Inflation pressure increases
This is why crude and USD/INR should increasingly be watched together.
What Should Global Investors Watch Next?
Five indicators could tell us whether the $100-oil episode is temporary or becoming something more serious.
Brent Crude
Holding above $100 is more important than briefly crossing it.
A sustained move toward $110–$120 would materially change the macro discussion.
Diesel and Refining Margins
Extreme refined-product prices could indicate that the real economy is facing tighter fuel supplies than crude alone suggests.
U.S. Treasury Yields
If oil and bond yields rise simultaneously, equity markets face a much tougher environment.
Dollar and Emerging-Market Currencies
A stronger dollar combined with expensive oil would be particularly difficult for oil-importing emerging economies.
Energy vs Consumer Stocks
Continued energy-sector outperformance alongside weakness in transportation, consumer and rate-sensitive stocks would suggest investors are actively repositioning for a prolonged oil shock.
The Bigger Question: Can Earnings Absorb $100 Oil?
There is one reason global equities have remained surprisingly resilient.
Corporate earnings expectations remain strong.
In the United States, analysts currently expect substantial year-on-year S&P 500 earnings growth in the coming reporting season, supported particularly by energy and technology.
That gives the stock market a buffer.
But the buffer is not unlimited.
Companies now need to overcome:
Higher interest rates
Higher energy prices
Higher wage costs
and, in some regions,
slower economic growth.
If earnings remain strong, equities could continue absorbing $100 oil.
If profit margins begin deteriorating, investors may suddenly become much less comfortable with today's valuations.
LiveWorldMarket View
The return of $100 oil does not automatically mean a global equity correction is coming.
But the market impact becomes increasingly significant the longer crude remains above triple digits.
The most exposed areas are likely to be economies heavily dependent on imported energy and sectors with high fuel or transportation costs and limited pricing power.
That puts India, parts of Europe and Japan among the markets worth monitoring closely.
At the sector level, airlines, transportation, autos, chemicals and selected consumer companies face the clearest pressure.
Meanwhile, oil producers and parts of the broader energy sector could remain relative beneficiaries.
The most important signal, however, may not come from oil itself.
Watch what happens to inflation expectations and bond yields.
If Brent remains above $100 while government bond yields continue climbing, the market will no longer be dealing with two separate risks.
It will be dealing with one interconnected problem:
An energy shock keeping inflation and the global cost of capital higher for longer.
That would be the real $100 oil test for world stock markets.
Continue Exploring LiveWorldMarket
Disclaimer: This article is for informational and educational purposes only and should not be considered investment advice.
Comments (0)
Be the first to comment.
About the author
NISM-Series-X-A Investment Adviser Level 1 examination completed
Amit writes about Indian equity markets, technical analysis, macro themes and the day-to-day mechanics of trading, with a focus on making the flow of global markets legible for retail investors. He has completed the NISM-Series-X-A Investment Adviser Level 1 examination.
You May Also Like
Starlink $8B Spectrum Deal: Telecom Stocks Fall, Towers Rise
Technology & Sectors · Oct 10, 2026 · 10 min read
Starlink's $8 Billion Spectrum Deal: Why Telecom Stocks Fell While Tower Shares Surged A single spectrum deal has sent shockwaves through the global telecommunications industry. On October 8, SpaceX announced an agreement to acquire nationwide 800 MHz wireless spectrum from Grain Management, marking a significant step toward expanding its Starlink Mobile business. The…
Read more...
Two-Thirds of S&P 500 Stocks Rose—Why Did the Index Fall? AI Warning
Technology & Sectors · Oct 9, 2026 · 11 min read
The AI Boom Is Turning Into a $100 Billion Debt Race: Could Borrowing Costs Become the Next Risk for Tech Stocks? For the past three years, artificial intelligence has been one of the biggest forces driving global stock markets. From Nvidia's extraordinary rise to the massive expansion of AI data centres, investors have rewarded companies promising to build the infrastructure…
Read more...
AI Debt Boom 2026: Could Borrowing Costs Hit Tech Stocks?
News · Oct 8, 2026 · 11 min read
The AI Boom Is Turning Into a $100 Billion Debt Race: Could Borrowing Costs Become the Next Risk for Tech Stocks? For the past three years, artificial intelligence has been one of the biggest forces driving global stock markets. From Nvidia's extraordinary rise to the massive expansion of AI data centres, investors have rewarded companies promising to build the infrastructure…
Read more...
Stocks Hit Record Highs While Bond Yields Flash a Warning: Which Market Is Right?
Global Markets & Economy · Oct 6, 2026 · 9 min read
Stocks Are Hitting Records While Bonds Flash a Warning: Which Market Is Right? Something unusual is happening across global financial markets. Stocks are celebrating. Bonds are warning. On October 6, global equities climbed to their highest level in roughly two weeks. The S&P 500 reached another record, while the technology-heavy Nasdaq extended its run of all-time highs. The…
Read more...
France Bond Spread Hits 2011-Era Extreme: Is Europe’s Debt Risk Returning?
Global Markets & Economy · Oct 6, 2026 · 9 min read
France’s Bond Spread Just Hit a 2011-Era Extreme: Is Europe Quietly Re-Entering a Sovereign-Debt Risk Trade? For much of 2026, investors have been focused on the Federal Reserve, oil, inflation and the extraordinary resilience of AI-driven equity markets. But another risk is quietly emerging in Europe. The gap between France’s 10-year government bond yield and Germany’s…
Read more...
Why Are Defense Stocks Falling Despite Rising Global Military Spending?
Geopolitics & Trade · Oct 5, 2026 · 12 min read
Global military spending is rising. Weapons inventories are being rebuilt. Major defense contractors are receiving some of the largest multiyear orders in years. Yet U.S. defense stocks have been falling. The iShares U.S. Aerospace & Defense ETF has declined by as much as 18.2% from its August 14 record high and has posted seven consecutive weekly losses, its longest such…
Read more...
U.S. Jobs Fall to 29,000 as Nasdaq Hits Record: Why Weak Data Is Lifting Stocks
Trend · Oct 4, 2026 · 11 min read
U.S. Jobs Just Fell to 29,000—So Why Did the Nasdaq Hit a Record High? The ‘Bad News Is Good News’ Trade Is Back The latest U.S. jobs report delivered what would normally look like bad news for the economy. The United States added only 29,000 jobs in September, far below expectations. The unemployment rate increased to 4.2%. Annual wage growth slowed to 3.0%. And employment…
Read more...
China’s Fuel Export Squeeze: Could Asia’s $50 Refining Margins Become the Next Inflation Shock?
Commodities & Energy · Oct 3, 2026 · 10 min read
China’s Fuel Export Squeeze: Could Asia’s $50 Refining Margins Become the Next Inflation Shock? Global investors have spent much of 2026 watching crude oil. But another part of the energy market may now deserve just as much attention: the cost of refining crude oil into the fuels that households and businesses actually use. Tightening Chinese fuel exports and constrained…
Read more...
Global Bond Selloff: Why Government Debt Is Becoming a Bigger Risk Than the Fed
Global Markets & Economy · Oct 2, 2026 · 12 min read
The Fed Isn't the Biggest Problem Anymore: Why the Global Bond Market Is Suddenly Worried About Government Debt For years, investors trying to understand bond markets focused on one question: What will the Federal Reserve do next? Will the Fed raise interest rates? Will it pause? When will it cut? That framework still matters. But something more fundamental is beginning to…
Read more...
AI Is Reviving Asia's Factories: Is Global Manufacturing Finally Turning?
Global Markets & Economy · Oct 1, 2026 · 12 min read
AI Is Reviving Asia’s Factories: Is the Global Manufacturing Cycle Finally Turning? For the past few years, artificial intelligence has primarily been viewed as a technology and stock-market story. AI stocks surged. Semiconductor companies expanded production. Technology giants committed hundreds of billions of dollars to data centres and computing infrastructure. Now…
Read more...