
Global Stock Market Outlook 2026: The Next 3–6 Months
Global stock markets entered September 2026 with strong headline returns—but the surface is calmer than the forces underneath. Artificial-intelligence spending remains a powerful earnings engine, emerging markets have outpaced developed-market benchmarks, and several economies continue to grow. At the same time, an energy shock, sticky inflation and rising government-bond yields have made the cost of capital a central risk again.
For the next three to six months, the most useful question is not whether every market will rise or fall together. It is which regions and sectors can continue producing earnings growth while interest rates stay restrictive, and which valuations already assume an unusually favorable outcome.
Bottom line The base case is a choppy, selective market rather than a straight-line rally or a global bear market. Earnings growth and AI investment can support equities, but oil prices, bond yields and policy uncertainty are likely to cause sharper rotations between technology, value, exporters, banks and domestic-demand shares.
Global stock market snapshot: strong returns, uneven foundations
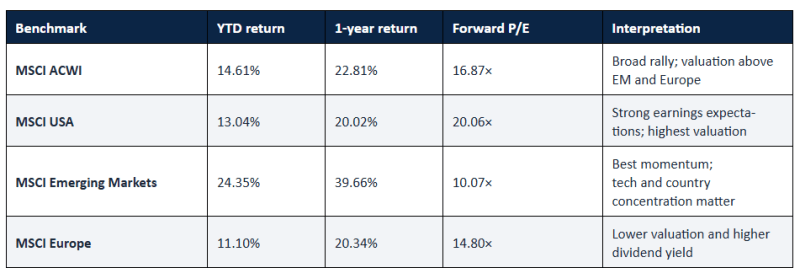
The broad global rally has remained intact. On a gross-return basis in U.S. dollars, the MSCI All Country World Index gained 14.61% year to date through 31 August 2026 and 22.81% over the previous 12 months. Emerging markets were the standout: the MSCI Emerging Markets Index returned 24.35% year to date and 39.66% over 12 months. The MSCI USA Index rose 13.04% year to date and 20.02% over 12 months. Europe also advanced, with the MSCI Europe Index up 11.10% year to date on a net-return basis.
These figures show that leadership has broadened beyond the U.S., but they do not mean risk has disappeared. Emerging-market performance has been helped by a concentrated technology supply chain: Taiwan Semiconductor Manufacturing alone represented 15.14% of the MSCI Emerging Markets Index, while Samsung Electronics and SK Hynix together accounted for another 12.68% at the end of August. In developed markets, the MSCI World Index carried a 29.81% technology weight and a 72.14% U.S. country weight.

Source: MSCI index factsheets dated 31 August 2026. ACWI, USA and Emerging Markets figures are gross returns; Europe figures are net returns. Index returns are not directly investable and past performance does not predict future performance.
The macro backdrop: growth is holding up, but forecasts disagree
The global economy is not in a uniform recession. The International Monetary Fund projects global growth of 3.0% in 2026 and 3.4% in 2027, arguing that technology momentum is partly offsetting the drag from conflict and higher energy costs. The World Bank is more cautious, projecting 2.5% growth in 2026 and highlighting downside risks from commodity disruption and geopolitical strain.
The gap between those forecasts is itself important. It tells investors that the range of plausible outcomes is unusually wide. Equity prices can remain supported if corporate earnings track the stronger path. If energy costs stay high and consumption weakens, earnings estimates could be revised lower even without a formal global recession.
Five forces likely to shape markets through early 2027
1. Bond yields may matter more than policy-rate cuts
The U.S. Federal Reserve held its policy range at 3.50%–3.75% in July, with three members preferring a quarter-point increase. That division shows why markets should not assume an automatic easing cycle. Even if short-term policy rates eventually decline, long-term yields can remain elevated when inflation expectations, fiscal borrowing and term premiums rise.
For equities, higher long-term yields reduce the present value of distant profits. This pressure is usually strongest in expensive growth shares, property-related businesses and companies that depend heavily on refinancing. Banks and insurers can benefit from higher yields only when credit quality and loan demand remain healthy.
2. Oil is both an inflation shock and a regional earnings shock
Higher oil prices do not affect every market equally. Energy exporters and integrated oil producers may receive an earnings boost, while airlines, chemicals, logistics companies and energy-importing economies face pressure on costs and household purchasing power. The ECB kept rates unchanged in July but explicitly warned that energy prices were well above pre-conflict levels and that the full inflation impact had not yet appeared.
India is especially worth watching because its domestic growth outlook remains firm but its current account, rupee and inflation can be sensitive to imported energy. Investors should therefore read crude oil, USD/INR and foreign institutional flows together—not as isolated indicators.
3. AI moves from excitement to evidence
AI-related capital spending continues to support semiconductors, data centres, networking, power equipment and selected software companies. The next phase, however, is likely to reward proof: revenue growth, utilisation, margins and credible returns on large capital budgets. A company can participate in a powerful theme and still underperform if its valuation already discounts years of flawless execution.
The opportunity is also wider than mega-cap platforms. Power generation, grid equipment, cooling systems, industrial automation, memory chips and advanced manufacturing can benefit from the same investment cycle. The risk is that several of these areas become crowded at once, leaving prices vulnerable to even modest earnings disappointments.
4. Global leadership is broadening—but concentration remains
Emerging markets and value strategies have outpaced the broad global index in 2026, suggesting investors are looking beyond the previous narrow set of winners. Yet concentration has changed form rather than disappeared. Emerging-market benchmarks are heavily influenced by Asian semiconductor companies, while developed-market benchmarks remain dominated by the United States and technology.
This means geographic diversification should be evaluated by underlying revenue and sector exposure. Owning several country funds may still produce the same semiconductor, dollar or commodity sensitivity. True diversification comes from combining different earnings drivers, balance sheets and currency exposures.
5. Currency moves can change the return received by Indian investors
An overseas index may rise in local currency while an Indian investor earns a different return after the rupee conversion. A stronger rupee can reduce the INR value of foreign gains; a weaker rupee can add to them. Currency hedging also has a cost and may behave differently as interest-rate gaps change. For readers comparing international funds, index returns and portfolio returns should therefore not be treated as identical.
Regional outlook for the next 3–6 months
United States: earnings resilience versus valuation risk
The U.S. economy grew at a 1.5% annualised rate in the second quarter of 2026, slower than the 2.1% pace recorded in the first quarter. Corporate profits from current production nevertheless increased sharply in the second quarter, providing a fundamental cushion for equities.
The tension is valuation. At the end of August, the MSCI USA Index traded at 20.06 times forward earnings compared with 16.87 times for MSCI ACWI, 14.80 times for Europe and 10.07 times for emerging markets. The ten largest MSCI USA constituents represented 36.89% of the index. Strong companies can justify premium multiples, but a concentrated, expensive market has less room for disappointing growth or higher yields.
Near-term view: neutral to moderately constructive, with a preference for earnings quality over speculative duration. Broader participation from industrials, healthcare, financials and profitable mid-sized companies would make the rally healthier. A renewed jump in real yields or weaker AI monetisation would be the clearest risks.
Europe: cheaper valuations, but energy sensitivity remains
Euro-area GDP rose 0.4% quarter on quarter in Q2 2026 after being flat in Q1, while employment increased 0.1%. The region therefore has modest positive growth rather than a deep contraction. European equities also trade at a lower forward multiple than the U.S. and offer a higher dividend yield, which can attract investors when valuation discipline returns.
The challenge is the energy channel. High energy costs can squeeze manufacturers and consumers, while a fragile global trade cycle affects exporters. Banks may benefit from firmer yields, and defence, infrastructure and selected industrial companies have structural support. Luxury and consumer exporters remain linked to Chinese demand.
Near-term view: selectively constructive, especially where earnings are less dependent on cheap energy. The case improves if energy prices ease and economic sentiment holds; it weakens if inflation forces a more restrictive ECB path.
China and Hong Kong: policy support meets uneven domestic demand
China’s GDP grew 4.7% year on year in the first half of 2026, slowing from 5.0% in the first quarter to 4.3% in the second. July’s official manufacturing PMI fell to 49.2, below the 50 line that separates expansion from contraction. This combination suggests that headline growth is continuing, but momentum in parts of industry and domestic demand is uneven.
Chinese and Hong Kong equities retain valuation appeal and can respond sharply to credible measures that improve property confidence, household demand or private-sector investment. However, short rallies driven mainly by policy headlines may fade if earnings and credit demand do not follow.
Near-term view: tactical and policy-sensitive. Better consumer data, firmer property sales and improving new orders would strengthen the case; renewed property stress, trade restrictions or weak private demand would keep risk elevated.
Japan: nominal-growth opportunity with rate and yen risk
The Bank of Japan expects the economy to keep growing moderately in fiscal 2026, supported by solid wage gains and global AI demand, even as high oil prices weigh on real income. It also expects inflation to move clearly above 2% from the second half of the fiscal year. That backdrop can support bank margins and companies with pricing power, but it also increases the chance of further monetary normalisation.
Near-term view: constructive but volatile. Corporate reform, wages and semiconductor demand remain supportive. Investors should watch the yen and Japanese government-bond yields: rapid currency appreciation can pressure exporters, while disorderly yield moves can reduce equity valuations.
India: superior growth, imported-inflation sensitivity
India remains the strongest major-economy growth story in this comparison. The RBI projects real GDP growth of 6.7% for FY2026–27 and CPI inflation of 5.0%, while keeping the repo rate at 5.25% with a neutral stance. The Nifty 50 closed at 23,897.70 and the Sensex at 76,515.43 on 4 September, according to RBI market data.
Domestic consumption, capital expenditure, financial deepening and formalisation remain long-term supports. In the near term, however, equity returns will depend on earnings delivery versus valuation, rural and urban demand, bank credit quality, monsoon outcomes, crude oil and the direction of foreign flows.
Near-term view: structurally constructive but not insulated from global volatility. A stable rupee, moderating oil and broad earnings growth would be supportive. Persistent oil strength, weaker margins or foreign selling could keep the headline index range-bound even if selected sectors perform well.
Three scenarios for global equities

What investors can monitor without trying to predict every headline
Earnings breadth: Are profit upgrades spreading beyond a few large technology companies?
Bond yields: Are long-term yields rising because growth is healthy, or because inflation and fiscal risk are worsening?
Oil and freight: Are input costs becoming a temporary shock or feeding into core inflation and margins?
Market breadth: Are more stocks and sectors participating, or are indices being carried by a small group?
Credit spreads: Are corporate borrowing-risk premiums stable, or warning that financial stress is building?
Currencies: How are the dollar, yen, euro and rupee changing the return and inflation picture?
Policy transmission: Are rate changes improving demand, or are households and companies still constrained by financing costs?
Practical portfolio principles for uncertain markets
Diversification is more useful than a single-point forecast. Investors can spread risk across regions, sectors, business models and time rather than relying on one index or theme. The correct mix depends on financial goals, time horizon, cash-flow needs and capacity for loss.
Valuation should be paired with quality. A low multiple can reflect genuine business weakness, while a premium valuation can be supported by durable cash flow. Balance-sheet strength, interest coverage, pricing power and free-cash-flow conversion are more informative when borrowing costs are high.
Staggered investing can reduce timing pressure. Investors who are building long-term exposure may find periodic deployment more manageable than making one large decision around a central-bank meeting or geopolitical headline. This does not eliminate loss risk, but it reduces dependence on a single entry point.
Leverage deserves particular caution. A volatile but survivable market move can become a permanent capital loss when positions are financed with borrowed money or derivatives that force an exit. Products should be understood before use, including currency, liquidity, tracking-error and tax implications.
Conclusion: expect opportunity, but demand evidence
The global stock market outlook for the next three to six months is neither uniformly bullish nor uniformly bearish. The world economy is still expanding, corporate profits remain supportive in several regions and AI investment is creating real demand. Those positives are balanced by expensive U.S. valuations, concentrated benchmarks, higher energy costs and the return of bond-market discipline.
A reasonable base case is continued volatility with opportunities shifting between regions and sectors. The strongest market will not necessarily be the one with the fastest GDP growth, and the cheapest market will not automatically produce the best return. Earnings delivery, valuation, currency and policy will interact.
For Indian readers, the most practical approach is to use global markets as context—not as a daily signal to trade. Follow oil, yields, the dollar, earnings revisions and market breadth. Then connect those signals to your own horizon and risk capacity. The next phase is likely to reward patience, diversification and evidence more than confident forecasts.
Frequently asked questions
What is the global stock market outlook for the rest of 2026?
The base case is positive but uneven: global growth remains above zero and earnings provide support, while oil, inflation, bond yields and high valuations can produce corrections and rapid sector rotation.
Could global stock markets fall even if GDP keeps growing?
Yes. Equity prices depend on the gap between results and expectations. Markets can fall during economic growth if earnings disappoint, valuations contract or interest rates rise.
Which region looks cheapest in September 2026?
On MSCI forward P/E data at 31 August, emerging markets were cheaper than Europe and the U.S. Lower valuation can improve long-term return potential, but it may also reflect higher policy, currency, governance or concentration risk.
Why do U.S. bond yields affect stocks worldwide?
U.S. Treasury yields influence the global discount rate, funding costs and dollar liquidity. Higher yields can reduce the relative appeal of equities and pressure markets that depend on foreign capital.
How do oil prices affect the Indian stock market?
India imports much of its crude oil. Sustained price increases can raise inflation, pressure the rupee and margins, and affect monetary policy, although domestic producers and some energy businesses may benefit.
Is this a prediction of index targets?
No. This research uses scenarios and observable indicators. It does not provide a guaranteed direction, return or personalised investment recommendation.
Suggested internal links for LiveWorldMarket
Live global indices, futures, commodities and currencies
Currency and Commodity Dashboard
Global Stock Market Returns in 2026
Sources and methodology
Market-return and valuation comparisons use broad MSCI benchmarks as of 31 August 2026. Economic and policy claims use primary sources from international institutions, central banks and national statistical agencies. Return conventions are stated where figures are compared. Outlook statements are LiveWorldMarket analysis based on the cited evidence; they are scenarios, not forecasts with guaranteed outcomes.
1. International Monetary Fund — World Economic Outlook Update: Global Economy in Crosscurrents of War and Technology (8 July 2026).
2. World Bank — Global Economic Prospects (June 2026).
3. MSCI — MSCI Emerging Markets Index Factsheet (31 August 2026).
4. MSCI — MSCI USA Index Factsheet (31 August 2026).
5. MSCI — MSCI World Index Factsheet (31 August 2026).
6. MSCI — MSCI Europe Screened Index Factsheet (includes parent-index data) (31 August 2026).
7. U.S. Federal Reserve — Federal Reserve issues FOMC statement (29 July 2026).
8. European Central Bank — Monetary policy decisions (23 July 2026).
9. U.S. Bureau of Economic Analysis — GDP: Second Estimate and Corporate Profits, Second Quarter 2026 (26 August 2026).
10. Eurostat — GDP and employment in the euro area, Q2 2026 (14 August 2026).
11. National Bureau of Statistics of China — Preliminary Accounting Results of GDP for Q2 and H1 2026 (17 July 2026).
12. National Bureau of Statistics of China — Purchasing Managers’ Index for July 2026 (1 August 2026).
13. Bank of Japan — Outlook for Economic Activity and Prices (30 July 2026).
14. Reserve Bank of India — RBI Bulletin: Monetary Policy Statement, August 2026 (25 August 2026).
15. Reserve Bank of India — Current Rates and Capital Market Data (4 September 2026).
Editorial and financial disclaimer
Important This article is for educational and informational purposes only. It is not investment, tax or legal advice; it does not recommend any security, fund, market or strategy; and it does not promise returns. Market data may be delayed or revised. Readers should verify information with official sources and consult a SEBI-registered investment adviser where personalized advice is required. Investments and derivatives involve risk, including possible loss of capital.
Comments (0)
Be the first to comment.
About the author

NISM-Series-X-A Investment Adviser Level 1 examination completed
Amit writes about Indian equity markets, technical analysis, macro themes and the day-to-day mechanics of trading, with a focus on making the flow of global markets legible for retail investors. He has completed the NISM-Series-X-A Investment Adviser Level 1 examination.
You May Also Like

US Midterm Elections 2026: Impact on Stocks, Dollar & India
Global Markets & Economy · Nov 4, 2026 · 10 min read
US Midterm Elections 2026: Why Treasury Yields, the Dollar and Indian Stocks Could React More Than Wall Street Key Takeaway: Democrats have won control of both chambers of the US Congress in the 2026 midterm elections, creating a divided government under President Donald Trump. The immediate market reaction has been revealing: US Treasury yields declined, the dollar weakened…
Read more...
Apple Overtakes Nvidia: Is Lower AI Spending Winning?
Technology & Sectors · Nov 2, 2026 · 9 min read
Apple Overtakes Nvidia as World's Most Valuable Company Ahead of Earnings: Is Spending Less on AI Becoming Wall Street's Winning Strategy? Key takeaway: Apple has reclaimed the title of the world's most valuable publicly traded company, overtaking Nvidia as investors reassess the enormous cost of artificial intelligence infrastructure. With Apple's upcoming earnings in focus…
Read more...
ExxonMobil Refining Profits Surge: Impact on Indian Oil Stocks
Commodities & Energy · Nov 1, 2026 · 8 min read
ExxonMobil's Refining Profits Overtake Oil Drilling for First Time in 6 Years: Why India's Oil Stocks May Miss the Windfall Key Takeaway: ExxonMobil's refining business has emerged as a bigger earnings contributor than oil production, highlighting an extraordinary shift in global energy markets. But Indian oil companies such as IOC, BPCL and HPCL face a different challenge…
Read more...
Fed Decision and Microsoft–Google Earnings: Two Critical Tests for the AI Stock Market Rally
Global Markets & Economy · Oct 28, 2026 · 15 min read
Global stock markets are approaching one of the most important financial evenings of October 2026. The U.S. Federal Reserve is preparing to announce its latest interest-rate decision, while Microsoft and Alphabet, Google's parent company, are scheduled to publish quarterly earnings after Wall Street closes. These developments arrive as investors reassess the sustainability of…
Read more...
JetBlue Stock Surges 20%, Bond Yield Tops 30%: Warning?
Global Markets & Economy · Oct 28, 2026 · 16 min read
JetBlue Stock Surges 20% While Its Bonds Yield Over 30%: Is Airline Debt Flashing a Warning for Investors? Something unusual is happening in the U.S. airline industry. Shares of JetBlue Airways surged approximately 20% on October 27, after the airline raised its revenue outlook and attempted to reassure investors about its financial position. But an entirely different story…
Read more...
US Consumer Staples Rally 9.6%: FMCG Valuation Risk for India
Global Markets & Economy · Oct 25, 2026 · 16 min read
US Consumer Staples Surge 9.6% as Valuations Overtake Tech: Is the Safe-Stock Trade Becoming a Trap for Indian FMCG Investors? Something unexpected is happening on Wall Street. As investors become increasingly cautious about expensive artificial intelligence stocks, money has been moving into an unlikely market leader: consumer staples. The U.S. consumer-staples sector has…
Read more...
SpaceX 80,000 Cell Sites: Will Starlink Challenge Jio & Airtel?
Global Markets & Economy · Oct 24, 2026 · 17 min read
SpaceX's 80,000 Cell-Site Plan Sends US Telecom Stocks Down 8%: Could Starlink Disrupt Jio and Airtel Next? A major shift may be emerging in the global telecommunications industry—and Wall Street has already started reacting. Shares of American telecommunications giants AT&T and T-Mobile plunged nearly 8% on October 23 after reports revealed that Elon Musk's SpaceX was…
Read more...
US 10-Year Treasury Yield Below 5%: Growth Shock Warning?
Central Banks & Rates · Oct 23, 2026 · 17 min read
US 10-Year Treasury Yield Falls Below 5% Despite $114 Oil: Is the Bond Market Warning of a Global Growth Shock? Something unusual is happening across global financial markets. The yield on the benchmark U.S. 10-year Treasury has fallen sharply below the psychologically important 5% level, even as Brent crude oil has surged toward $114 per barrel and technology stocks have…
Read more...
Brent Crude Tops $110: Impact on Indian Stocks & Earnings
Global Markets & Economy · Oct 22, 2026 · 14 min read
Brent Crude Tops $110: Why Indian Airlines, Paints and Tyre Stocks Face a Hidden Earnings Risk Brent crude oil has climbed above $110 per barrel, intensifying concerns that rising global energy prices could squeeze corporate profit margins, increase India's import costs and create further volatility in domestic equities. On October 22, Brent futures traded above $111 after…
Read more...
India Optical Fibre Exports Jump 158%: AI's Hidden Winners
Global Markets & Economy · Oct 21, 2026 · 12 min read
India's Optical Fibre Exports Jump 158% as Japan's Chip Shipments Surge 49%: The Hidden Winners of the AI Infrastructure Boom Artificial intelligence may be transforming the technology industry, but some of its most important economic beneficiaries are not necessarily the companies developing AI models. They may be the businesses manufacturing the physical infrastructure that…
Read more...