
F&O Trading Income Tax Guide for FY 2025–26 (AY 2026–27): Turnover, ITR, Tax Audit and Loss Rules
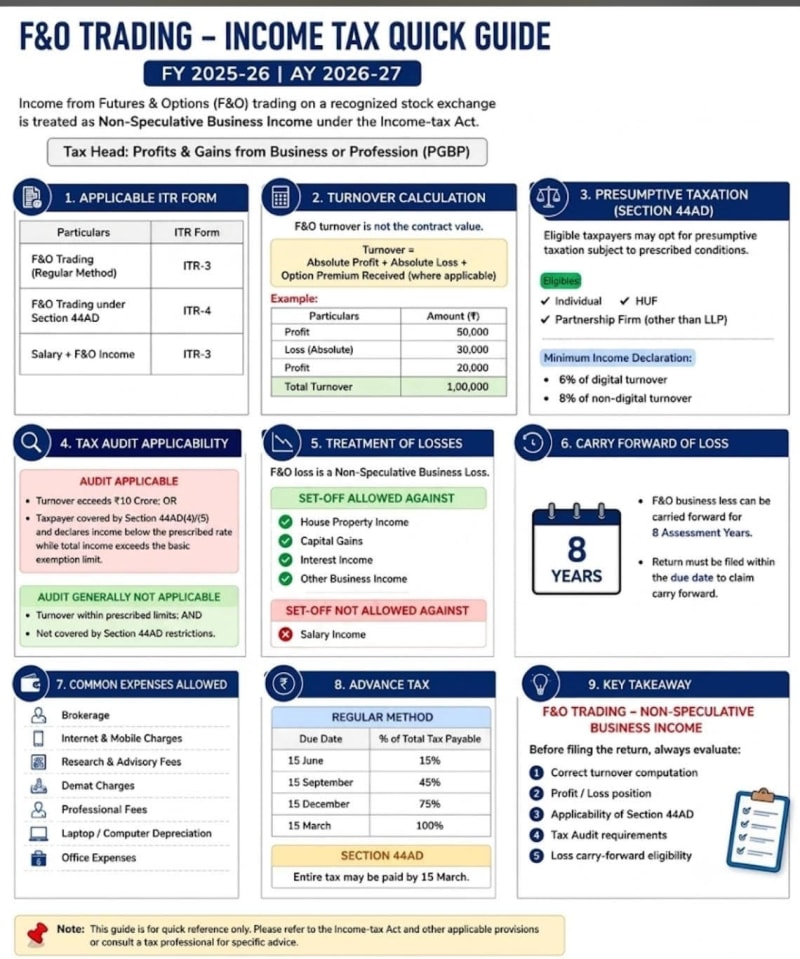
Futures and Options trading has become increasingly popular among Indian market participants. But when the financial year ends, many traders are unsure how their F&O profits and losses should be reported in the income-tax return.
Is F&O income treated as capital gains? Which ITR should be filed? How is turnover calculated? Does a loss require a tax audit? Can F&O losses be carried forward?
The answers are different from the tax treatment of ordinary long-term investing.
This guide explains the general tax treatment of exchange-traded F&O transactions for FY 2025–26, corresponding to Assessment Year 2026–27.

Important Note About the Income Tax Act, 2025
The Income Tax Act, 2025 came into force from 1 April 2026, replacing the Income-tax Act, 1961 for income earned from FY 2026–27 onward.
However, income earned during FY 2025–26 continues to be governed by the Income-tax Act, 1961.
Therefore, a return being filed for AY 2026–27 relates to FY 2025–26 and continues to follow the applicable provisions of the Income-tax Act, 1961.
The Income Tax Department has specifically clarified that returns for AY 2026–27 continue under the earlier Act even though those returns may be filed after 1 April 2026.
F&O Taxation at a Glance
 How Is F&O Income Classified?
One of the biggest misconceptions is that every transaction involving shares or stock-market instruments is taxed as capital gains.
That is not normally how eligible exchange-traded Futures and Options transactions are treated.
Under Section 43(5) of the Income-tax Act, 1961, eligible derivative transactions carried out on a recognised stock exchange are excluded from the definition of speculative transactions.
For an individual who conducts F&O trading as a business activity, the resulting profit or loss is generally reported under:
Profits and Gains from Business or Profession
This is why the tax-return requirements for an active F&O trader can be different from those of an investor who simply buys and holds shares.
Which ITR Form Is Generally Used for F&O Trading?
For individuals and Hindu Undivided Families having income from business or profession, ITR-3 is generally the relevant return.
The Income Tax Department describes ITR-3 as applicable to individuals and HUFs having income from profits and gains of business or profession.
A person should therefore not automatically file ITR-2 simply because the trading activity involves securities.
If F&O income is being treated as business income, ITR-3 will normally need to be considered.
Can an F&O Trader Use ITR-4?
ITR-4 is designed for eligible resident individuals, HUFs and firms other than LLPs whose income meets the prescribed conditions and whose business or professional income is reported under eligible presumptive-taxation provisions.
Section 44AD provides a presumptive-taxation framework for eligible businesses, subject to several conditions. Its normal turnover ceiling is ₹2 crore, which can increase to ₹3 crore where cash receipts do not exceed 5% of total turnover or gross receipts.
However, an F&O trader should not automatically assume that Section 44AD or ITR-4 applies simply because turnover falls below the threshold.
Eligibility depends on the taxpayer, nature of activity, reporting position and all applicable conditions.
Where there is uncertainty—particularly with substantial trading activity, losses, tax-audit considerations or multiple income sources—professional tax advice may be useful.
How Is F&O Turnover Calculated?
F&O turnover for income-tax and tax-audit purposes is not normally calculated by adding the full contract value of every Futures or Options trade.
That would produce an unrealistically large number because derivative contracts provide leveraged exposure to an underlying instrument.
For squared-off derivatives, tax-audit guidance has generally focused on the aggregate of favourable and unfavourable differences.
In simple terms, both profits and losses are considered as positive values while calculating turnover for this purpose.
Simple F&O Turnover Example
Assume a trader has the following closed transactions during the year:

The ₹35,000 loss is not deducted from the profitable transactions when calculating turnover. Its absolute amount forms part of turnover.
ICAI's tax-audit guidance describes the aggregation of favourable and unfavourable differences for derivatives. It also provides specific guidance for treatment of option premium and reverse trades.
Options Require Additional Care
Options can make turnover calculation more complicated.
Premium received on sale of options may need to be considered according to the applicable ICAI tax-audit methodology, but care is required to ensure that the same economic amount is not counted twice.
Because turnover can determine whether tax-audit provisions apply, traders with significant Options activity should reconcile their calculations with their broker's tax P&L statement, books of account and the latest ICAI guidance.
Is Contract Value the Same as Turnover?
No.
Suppose a trader buys and sells Nifty Futures contracts whose notional contract value runs into several crores during the year.
That does not necessarily mean the trader has several crores of F&O turnover for tax-audit purposes.
For derivatives, turnover calculation follows the applicable tax-accounting methodology rather than simply adding the underlying notional value of every contract.
This distinction is extremely important when evaluating tax-audit requirements.
When Is a Tax Audit Required?
Section 44AB contains the principal tax-audit rules for businesses.
For business, the standard turnover threshold is generally:
₹1 crore
However, the threshold can increase to:
₹10 crore
where cash receipts and cash payments each do not exceed the prescribed 5% limit.
Since most exchange-traded F&O transactions and broker settlements are electronic, the higher threshold can be relevant in appropriate cases.
However, turnover alone should not be treated as the only possible audit consideration.
Tax-audit applicability can also depend on matters such as presumptive-taxation provisions, profit declarations and the taxpayer's individual circumstances.
Therefore:
A trading loss does not automatically mean a tax audit is mandatory.
Likewise:
A profitable trader is not automatically exempt from audit.
The complete facts need to be examined.
Can Section 44AD Apply?
Section 44AD allows eligible taxpayers carrying on eligible businesses to report presumptive income at prescribed rates instead of calculating taxable profit under the normal business-income provisions.
Under the framework applicable to FY 2025–26, presumptive income is generally calculated at 8% of applicable turnover or gross receipts, with a 6% rate for qualifying non-cash receipts, subject to the statutory conditions.
The eligible-business turnover ceiling can rise from ₹2 crore to ₹3 crore where cash receipts do not exceed 5%.
For F&O traders, however, the decision to use presumptive taxation should not be made solely to simplify the return.
A taxpayer should first establish eligibility and understand the consequences, particularly when actual profits are lower than the presumptive amount or when losses have been incurred.
The Five-Year Rule Under Section 44AD
Section 44AD also contains an important continuity rule.
If an eligible taxpayer declares profits under Section 44AD and then fails to declare income in accordance with the scheme during one of the following five assessment years, the taxpayer may become ineligible to use Section 44AD for the subsequent five assessment years.
This means moving into and out of presumptive taxation can have consequences beyond a single tax return.
Traders should therefore understand the longer-term implications before choosing the presumptive route.
Can F&O Trading Expenses Be Deducted?
Where F&O income is reported under the normal business-income provisions, expenses incurred wholly and exclusively for the business may generally be considered for deduction, subject to the Income-tax Act and proper documentation.
Depending on the facts, relevant expenses could include brokerage, exchange charges, eligible data or software costs, professional fees, internet expenses attributable to the business and depreciation on qualifying assets used for the trading activity.
Personal expenses should not be claimed as business deductions merely because the taxpayer trades in the financial markets.
Proper records should be maintained to support material expenses.
If income is reported under an eligible presumptive-taxation scheme, separate deductions for normal business expenses are generally treated differently because the presumptive profit itself is intended to represent taxable business income.
What Happens If You Have an F&O Loss?
A genuine F&O business loss is not automatically wasted.
Because eligible exchange-traded F&O activity is generally treated as non-speculative business activity, the resulting business loss may be eligible for set-off and carry-forward under the applicable rules.
A non-speculative business loss cannot be set off against salary income.
If the loss cannot be fully absorbed in the same year, it may generally be carried forward for up to eight assessment years and used against eligible business income in subsequent years.
Timely Filing Is Very Important
To preserve the ability to carry forward eligible business losses, the return of loss generally needs to be filed within the prescribed due date.
The Income Tax Department's guidance confirms that business losses cannot ordinarily be carried forward unless the return is filed in accordance with the relevant loss-return requirements.
This is one reason F&O traders should avoid ignoring the ITR simply because they made a loss.
Advance Tax for F&O Traders
F&O traders can also become liable to pay advance tax.
Advance tax generally becomes applicable where the estimated tax liability for the year, after considering eligible credits such as TDS and TCS, is ₹10,000 or more.
For taxpayers following the normal advance-tax schedule, cumulative installments are generally:

Taxpayers using qualifying presumptive-taxation provisions have a different advance-tax schedule and may generally pay the full advance-tax liability by 15 March.
For active traders, estimating profit during the year can be difficult because profits may change sharply during volatile market periods.
Nevertheless, advance-tax requirements should not be ignored, as shortfalls or delays can result in interest.
Worked Example: F&O Profit and Tax Reporting
Consider an illustrative taxpayer who has the following income during FY 2025–26:
F&O trading profit before expenses: ₹4,20,000
Eligible business expenses: ₹70,000
Salary income: ₹8,00,000
The net F&O business income under normal business-income computation would be:
₹4,20,000 − ₹70,000 = ₹3,50,000
The ₹3.5 lakh does not become a separate special-rate F&O tax.
It forms part of the taxpayer's business income and is considered along with other taxable income when computing the overall tax liability under the applicable tax regime.
However, F&O turnover for tax-audit purposes is a separate calculation and should not be assumed to equal the ₹4.2 lakh trading profit.
The taxpayer must separately consider the applicable ITR, tax regime, turnover, audit position, advance tax and other tax provisions.
This example is only illustrative.
Keep Proper Trading Records
F&O traders should maintain organised records rather than relying only on the final net profit shown in a broker application.
Useful documentation may include the broker's tax P&L statement, trade book, ledger, contract notes, bank statements, expense records, turnover workings and copies of the income-tax return and supporting calculations.
Maintaining proper documentation becomes particularly important where trading volumes are high, losses are being carried forward or a tax audit is applicable.
Common Mistakes F&O Traders Should Avoid
Some of the most common problems arise from treating F&O trading like ordinary investing, calculating turnover using full contract value, assuming every loss requires a tax audit, ignoring loss-return filing deadlines, selecting the wrong ITR, claiming personal expenses as business costs, or choosing presumptive taxation without understanding its eligibility and long-term consequences.
Another frequent mistake is waiting until the last moment to obtain broker statements and calculate turnover.
Tax compliance is much easier when trading records are reconciled throughout the year.
Final Takeaway
The taxation of F&O trading is different from the taxation of ordinary delivery-based investing.
Eligible exchange-traded derivative transactions are generally treated as non-speculative transactions, and active traders normally report the resulting profit or loss under business income.
For individuals and HUFs with such business income, ITR-3 is generally the relevant return.
The most important point is that F&O turnover is not simply the total contract value traded. Turnover must be calculated using the appropriate tax-audit methodology, and that figure can influence whether audit provisions apply.
F&O losses can also have tax value because eligible business losses may be carried forward for up to eight assessment years, but timely filing of the return is important.
Traders should therefore focus on correct classification, accurate turnover calculation, proper records and timely compliance rather than treating taxation as an afterthought.
Official References
- Income Tax Department — ITR forms and guidance for individuals having income from business or profession for AY 2026–27.
- Income Tax Department — Income Tax Act, 2025 transition guidance confirming that AY 2026–27 remains governed by the Income-tax Act, 1961.
- Income Tax Department — Section 43(5), treatment of eligible derivative transactions on recognised stock exchanges.
- Income Tax Department — Sections 44AB and 44AD covering tax audit and presumptive taxation.
- Institute of Chartered Accountants of India — Guidance Note on Tax Audit under Section 44AB, including the revised 2026 publication.
- Income Tax Department — guidance on advance tax and carry-forward of business losses.
Disclaimer
This article is intended only for general educational and informational purposes. It does not constitute tax, legal, investment or financial advice.
Tax treatment can vary depending on an individual's facts, residential status, trading activity, income sources, accounting method and other circumstances. Tax laws, return forms and official guidance may also change.
Readers should verify the latest information from the Income Tax Department and consult a qualified tax professional or Chartered Accountant where appropriate before filing an income-tax return or making a material tax decision.
Comments (0)
Be the first to comment.
About the author

NISM-Series-X-A Investment Adviser Level 1 examination completed
Amit writes about Indian equity markets, technical analysis, macro themes and the day-to-day mechanics of trading, with a focus on making the flow of global markets legible for retail investors. He has completed the NISM-Series-X-A Investment Adviser Level 1 examination.
You May Also Like
Big Tech Gains $750B as AI Data Centre Stocks Crash
Global Markets & Economy · Nov 5, 2026 · 12 min read
Big Tech Gains $750 Billion After US Midterms, but AI Data-Centre Stocks Crash: Is Wall Street Rewarding Less AI Spending? Key Takeaway: Wall Street's reaction to the 2026 US midterm elections has exposed a surprising divide in the artificial intelligence investment boom. Established technology giants rallied, with five major companies on course to add more than $750 billion…
Read more...
US Midterm Elections 2026: Impact on Stocks, Dollar & India
Global Markets & Economy · Nov 4, 2026 · 10 min read
US Midterm Elections 2026: Why Treasury Yields, the Dollar and Indian Stocks Could React More Than Wall Street Key Takeaway: Democrats have won control of both chambers of the US Congress in the 2026 midterm elections, creating a divided government under President Donald Trump. The immediate market reaction has been revealing: US Treasury yields declined, the dollar weakened…
Read more...
Apple Overtakes Nvidia: Is Lower AI Spending Winning?
Technology & Sectors · Nov 2, 2026 · 9 min read
Apple Overtakes Nvidia as World's Most Valuable Company Ahead of Earnings: Is Spending Less on AI Becoming Wall Street's Winning Strategy? Key takeaway: Apple has reclaimed the title of the world's most valuable publicly traded company, overtaking Nvidia as investors reassess the enormous cost of artificial intelligence infrastructure. With Apple's upcoming earnings in focus…
Read more...
ExxonMobil Refining Profits Surge: Impact on Indian Oil Stocks
Commodities & Energy · Nov 1, 2026 · 8 min read
ExxonMobil's Refining Profits Overtake Oil Drilling for First Time in 6 Years: Why India's Oil Stocks May Miss the Windfall Key Takeaway: ExxonMobil's refining business has emerged as a bigger earnings contributor than oil production, highlighting an extraordinary shift in global energy markets. But Indian oil companies such as IOC, BPCL and HPCL face a different challenge…
Read more...
Fed Decision and Microsoft–Google Earnings: Two Critical Tests for the AI Stock Market Rally
Global Markets & Economy · Oct 28, 2026 · 15 min read
Global stock markets are approaching one of the most important financial evenings of October 2026. The U.S. Federal Reserve is preparing to announce its latest interest-rate decision, while Microsoft and Alphabet, Google's parent company, are scheduled to publish quarterly earnings after Wall Street closes. These developments arrive as investors reassess the sustainability of…
Read more...
JetBlue Stock Surges 20%, Bond Yield Tops 30%: Warning?
Global Markets & Economy · Oct 28, 2026 · 16 min read
JetBlue Stock Surges 20% While Its Bonds Yield Over 30%: Is Airline Debt Flashing a Warning for Investors? Something unusual is happening in the U.S. airline industry. Shares of JetBlue Airways surged approximately 20% on October 27, after the airline raised its revenue outlook and attempted to reassure investors about its financial position. But an entirely different story…
Read more...
US Consumer Staples Rally 9.6%: FMCG Valuation Risk for India
Global Markets & Economy · Oct 25, 2026 · 16 min read
US Consumer Staples Surge 9.6% as Valuations Overtake Tech: Is the Safe-Stock Trade Becoming a Trap for Indian FMCG Investors? Something unexpected is happening on Wall Street. As investors become increasingly cautious about expensive artificial intelligence stocks, money has been moving into an unlikely market leader: consumer staples. The U.S. consumer-staples sector has…
Read more...
SpaceX 80,000 Cell Sites: Will Starlink Challenge Jio & Airtel?
Global Markets & Economy · Oct 24, 2026 · 17 min read
SpaceX's 80,000 Cell-Site Plan Sends US Telecom Stocks Down 8%: Could Starlink Disrupt Jio and Airtel Next? A major shift may be emerging in the global telecommunications industry—and Wall Street has already started reacting. Shares of American telecommunications giants AT&T and T-Mobile plunged nearly 8% on October 23 after reports revealed that Elon Musk's SpaceX was…
Read more...
US 10-Year Treasury Yield Below 5%: Growth Shock Warning?
Central Banks & Rates · Oct 23, 2026 · 17 min read
US 10-Year Treasury Yield Falls Below 5% Despite $114 Oil: Is the Bond Market Warning of a Global Growth Shock? Something unusual is happening across global financial markets. The yield on the benchmark U.S. 10-year Treasury has fallen sharply below the psychologically important 5% level, even as Brent crude oil has surged toward $114 per barrel and technology stocks have…
Read more...
Brent Crude Tops $110: Impact on Indian Stocks & Earnings
Global Markets & Economy · Oct 22, 2026 · 14 min read
Brent Crude Tops $110: Why Indian Airlines, Paints and Tyre Stocks Face a Hidden Earnings Risk Brent crude oil has climbed above $110 per barrel, intensifying concerns that rising global energy prices could squeeze corporate profit margins, increase India's import costs and create further volatility in domestic equities. On October 22, Brent futures traded above $111 after…
Read more...